If a home workout leaves you injured, the paperwork can feel as discouraging as the injury itself. Insurance language is dense, and the path from treatment to payment usually requires a few deliberate steps. This piece focuses on matching the care you need with the benefits your plan actually offers. Read through the practical checkpoints below so you can act quickly and avoid surprise bills.
First Steps: Triage, Documentation, and Where to Go
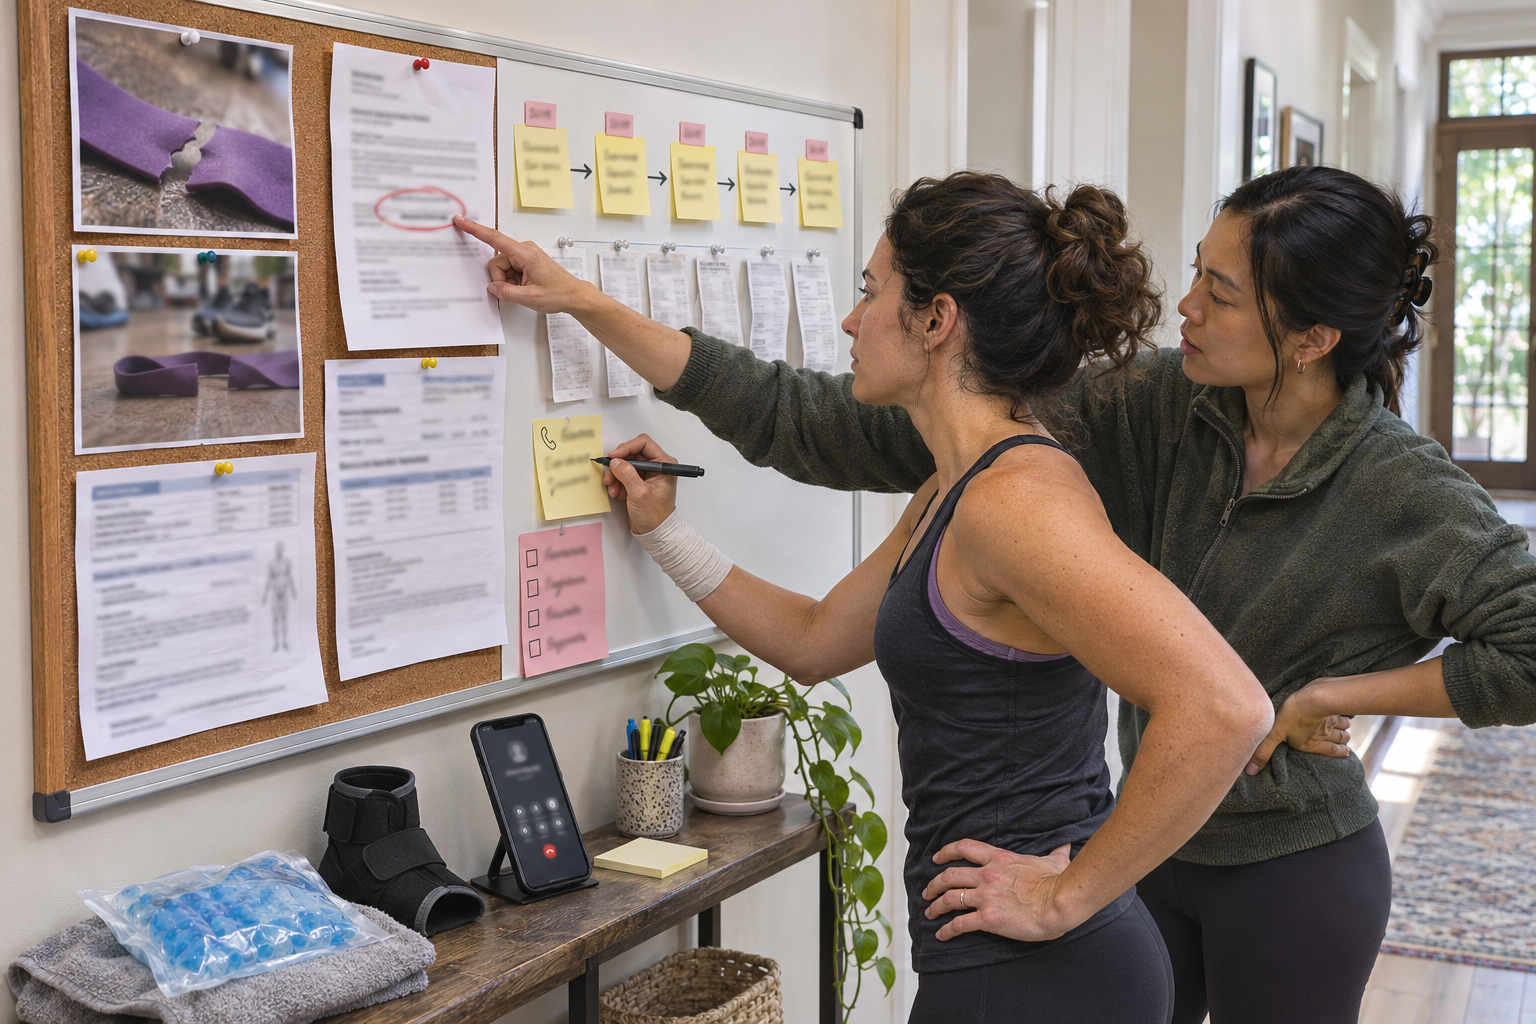
Decide immediately whether emergency care, urgent care, or telehealth is appropriate; the choice affects both cost and claims. Document the incident with notes and photos, get a medical record entry, and keep receipts for every visit or supply. Call your insurer if you are unsure which setting is in-network or covered at a lower cost. Confirming the right level of care early limits out-of-pocket expense and speeds claim processing.
Keep copies of all communications and the provider’s notes. This creates a paper trail that proves both the injury and the necessity of the care you received.
Understanding Coverage Details That Matter
Look at your plan’s deductible, co-insurance, and out-of-pocket maximums before assuming a visit is inexpensive. Rehabilitation, physical therapy, and durable medical equipment can be restricted to in-network providers or require prior authorization. Some plans treat home injuries like any other accidental claim, while others have exclusions tied to activities or equipment. Knowing these clauses helps you predict how much the insurer will pay and what you will owe.
Request an estimate from the provider and a benefits summary from your insurer. Those two documents together usually reveal the likeliest cost split.
Filing Claims and Handling Denials
Submit claims promptly, attaching medical records and itemized bills; lateness is a common reason for denial. If a claim is denied, read the denial letter carefully to identify the precise reason — coverage, coding, network status, or documentation gaps. Ask for a detailed explanation of benefits (EOB) and request corrections if provider billing codes were wrong. An organized appeal that points to missing records or misapplied policy language has a solid chance of success.
Keep a chronological log of calls, names, and reference numbers during the dispute. That record makes follow-up faster and reduces repeated explanations.
Conclusion
Match the level of care to your policy and document everything along the way. Ask for written estimates and an EOB to understand who will pay what. A careful, methodical approach reduces surprises and improves the chance of full reimbursement.