Home workouts are convenient and effective, but they can also lead to injuries that require medical attention. Knowing what your health plan covers before an incident reduces uncertainty and unexpected bills. This article outlines the policy elements to review and practical steps to improve your financial and care outcomes. Read on to learn how to audit coverage and prepare for a safer recovery.
Why policy review matters for at-home injuries
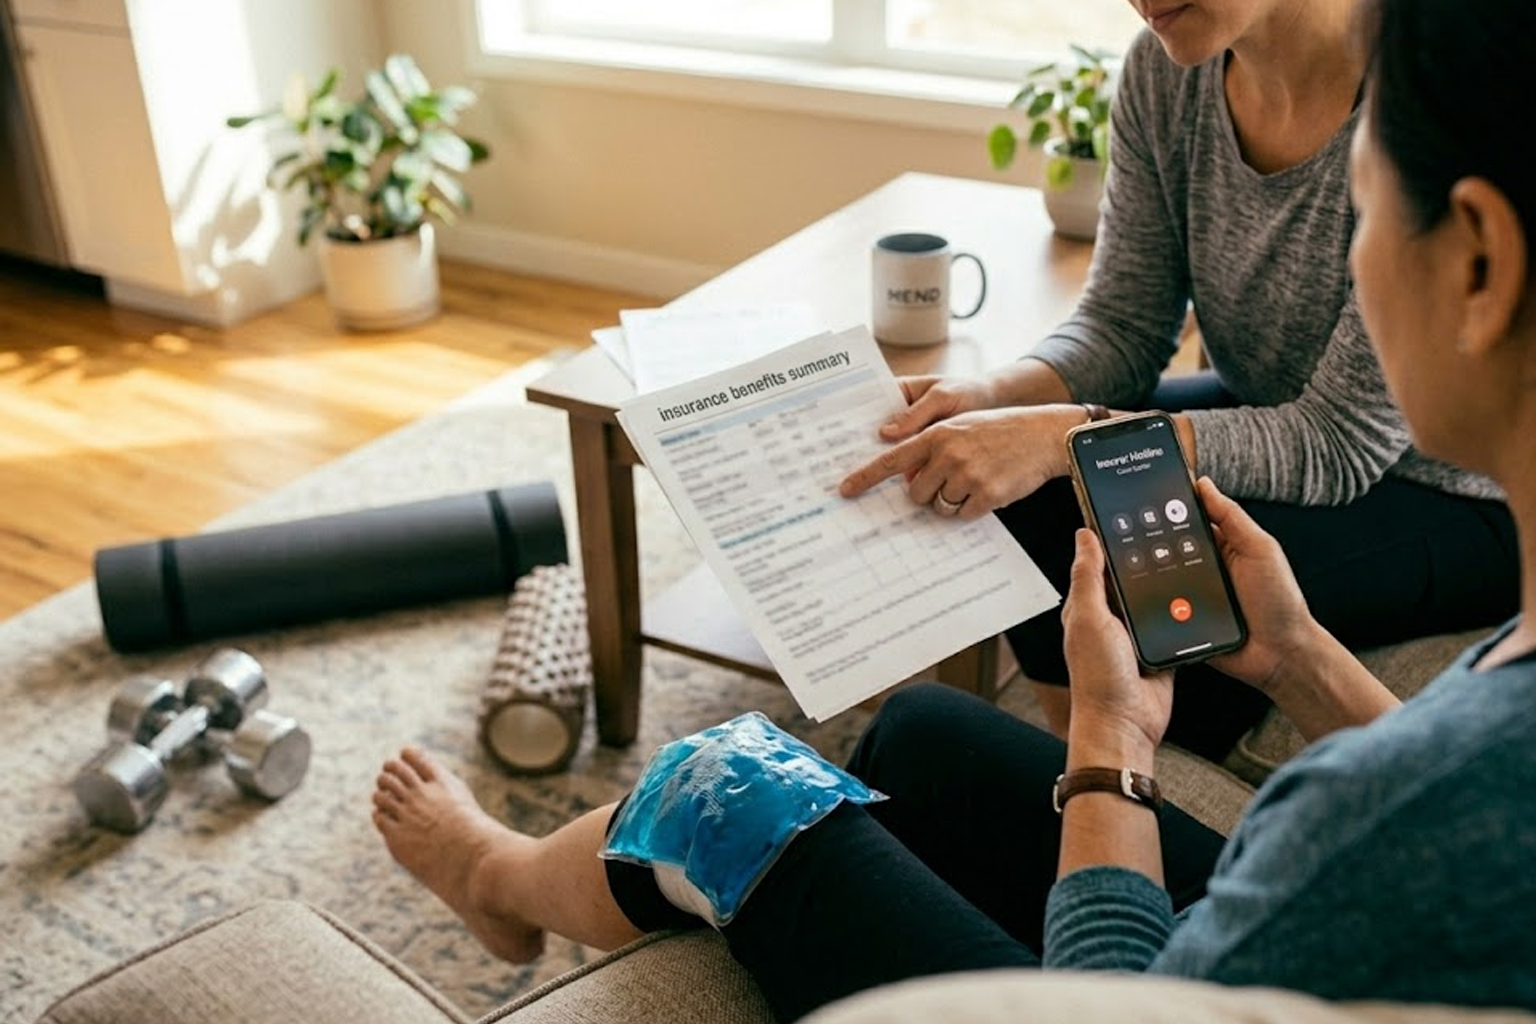
Many people assume a standard health plan will respond the same whether an injury happens at a gym or in the living room, but details vary. Coverage differences can affect emergency visits, imaging, physical therapy, and durable medical equipment. Understanding limits, exclusions, and prior authorization requirements helps you plan where to seek care. Ignorance of these specifics can lead to denials or large out-of-pocket expenses.
Taking the time to read key sections of your policy can save time and money. Keep a concise summary of relevant benefits in an easy-to-access place for quick reference after an incident.
Key coverage elements to check
Start by confirming emergency and urgent care coverage, network provider rules, and whether telehealth visits count toward deductible or copay. Review rehabilitation benefits for physical therapy frequency limits, cost-sharing tiers, and any cap on sessions. Check imaging and specialist referral requirements, as preauthorization or a primary care referral can change your financial responsibility. Also note exclusions for elective or non-covered treatments that might be used in recovery.
Document benefit limits and note the customer service contact for claim questions. Having this information reduces friction during a stressful time.
Managing claims and appeals after a home workout injury
If you file a claim for treatment, keep detailed records: dates, provider notes, receipts, and correspondence with the insurer. Promptly submit medical records and any preauthorization approvals to speed processing. If a claim is denied, follow the insurer’s appeal process and include supporting documentation explaining medical necessity. Understanding timelines for initial decisions and appeals helps you act quickly and preserve rights.
Consider asking your provider to include a clear treatment rationale in documentation if coverage is borderline. A well-documented appeal is more likely to succeed.
Practical steps to reduce out-of-pocket costs
Prevent unexpected expenses by choosing in-network providers, confirming prior approvals, and using telehealth for triage when appropriate. Compare estimated costs for different care settings—urgent care is often less expensive than an emergency department for non-life-threatening injuries. Maintain an emergency fund or health savings account to cover deductibles and copays. Regularly review and update your coverage during open enrollment to match your activity level and risk tolerance.
Small administrative steps taken now can lower financial stress after an injury. Regular policy reviews keep your coverage aligned with how and where you exercise.
Conclusion
Review your health plan details with an emphasis on emergency care, rehabilitation limits, and prior authorization rules. Keep clear documentation and a simple action plan for claims and appeals to reduce surprises. Proactive planning makes recovery from a home exercise injury more predictable and manageable.