After a home workout injury the immediate question is how policy rules affect costs.
Knowing where to seek care and how your plan shares expenses reduces surprises.
This article outlines practical tools within typical medical policies to lower out-of-pocket spending.
Use these steps to make faster, evidence-based decisions when an injury happens at home.
Understand cost-sharing and networks
Start by reviewing your deductible, copays, coinsurance, and out-of-pocket maximum to estimate potential expense exposure. In-network providers typically deliver lower negotiated rates so choosing one can materially cut bills. Also check how the plan treats urgent care, telehealth, and emergency visits since those categories often have different cost structures. Confirm whether rehabilitation services need separate limits or step therapy before assuming coverage.
When possible, prioritize in-network urgent care or telehealth for non-life-threatening injuries to control costs. If an emergency visit occurs, follow up with in-network providers for ongoing care to reduce future charges.
Streamline claims and documentation
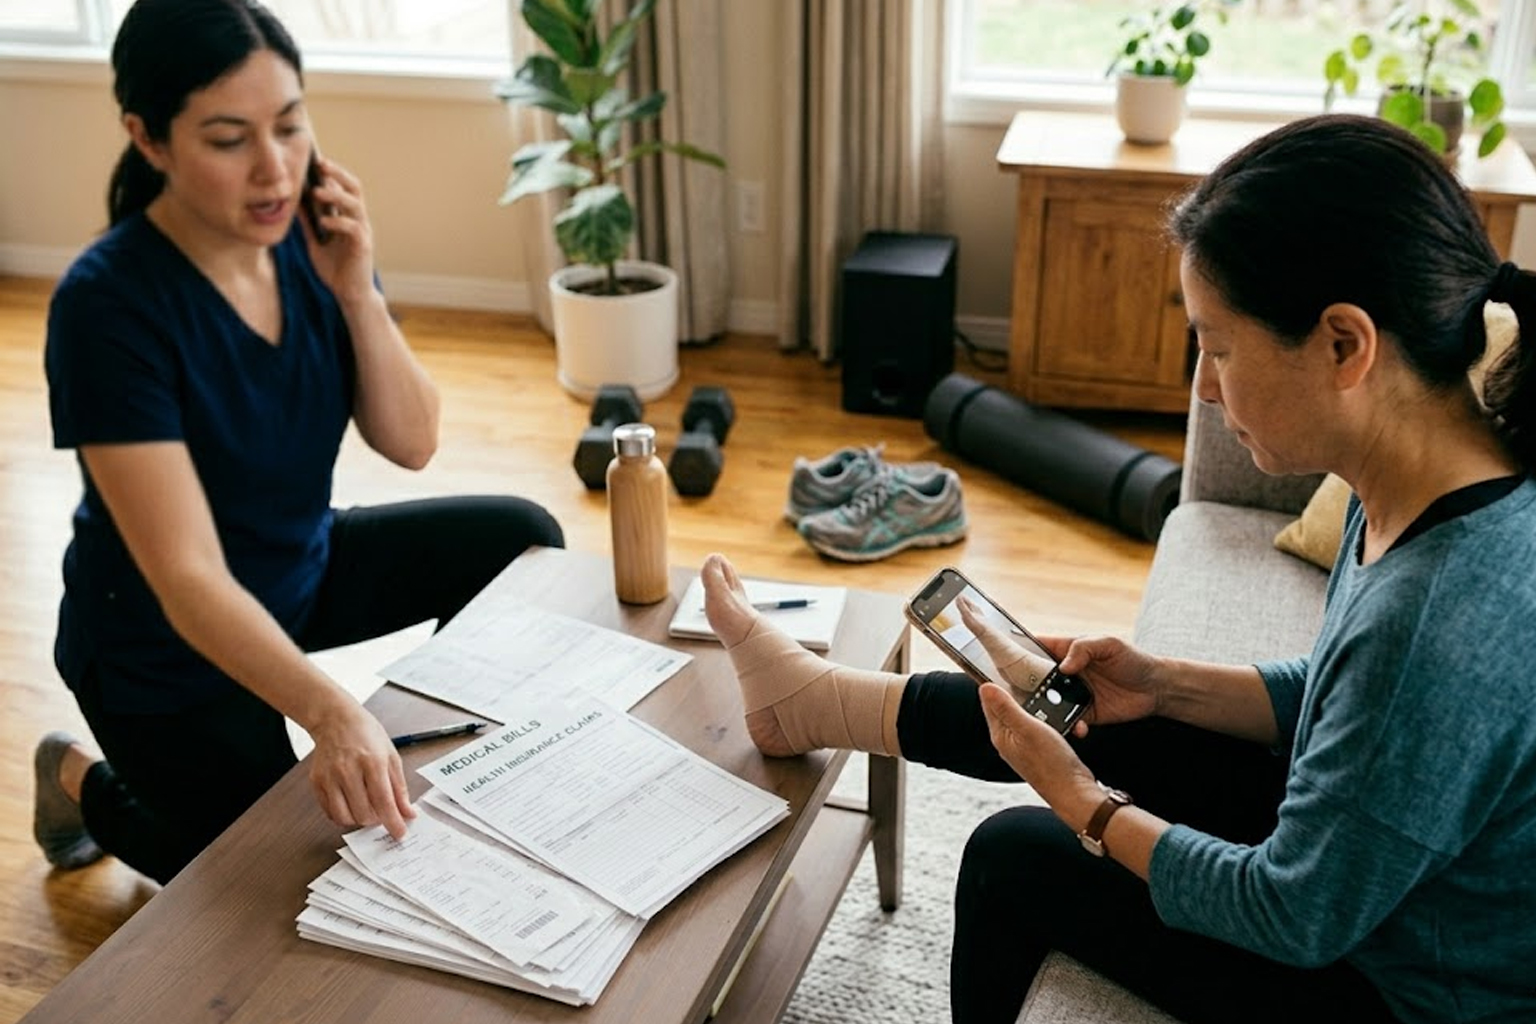
Accurate documentation speeds claims and supports appeals if charges are denied or out-of-network billed. Keep dated photos of the scene, notes about symptoms, receipts, provider names, and referral or authorization codes. Submit claims promptly and retain copies of explanations of benefits so you can compare billed versus allowed amounts. Knowing claim timelines and appeal procedures helps you contest errors and limit financial liability.
- Document: date, time, symptoms, photos.
- Collect: receipts, provider notes, authorization numbers.
- Track: claim IDs and EOBs.
Clear records make it easier to negotiate bills or provide evidence during an appeal. Most plans respond faster and resolve more favorably when claims are supported with concise documentation.
Use plan features and supplements
Explore telehealth, nurse lines, and case management options your plan offers to get care recommendations that lower costs. Flexible spending accounts or health savings accounts can buffer immediate out-of-pocket payments for deductible or copays. Consider short-term riders, accident policies, or rehabilitation add-ons if you expect regular risk from home training. Also review prior authorization rules for imaging and therapy to avoid surprise denials or retroactive charges.
Engaging plan resources early can prevent unnecessary high-cost care and smooth the administrative path. If coverage gaps remain, consult a benefits advisor or broker to evaluate supplemental options that match your home fitness routine.
Conclusion
Managing costs after a home workout injury starts with understanding your plan’s cost-sharing and network rules.
Document incidents thoroughly and use telehealth or in-network urgent care to limit expenses.
Leveraging plan features and supplemental products provides practical protection and peace of mind.