Setting up a routine at home can feel straightforward until an injury turns a short workout into phone calls and unpaid bills. Insurance policies are full of details that change who pays, how much, and where you can seek care after a fall or strain. Reading the relevant passages now reduces surprises later and helps you pick the right next step if care is needed. This piece highlights the specific policy items that most commonly influence costs after a home exercise injury.
Know which services your plan actually covers
Most plans list covered services and separate sections for emergency, urgent, and rehabilitative care. Coverage often differs for imaging, physical therapy, and follow-up visits, so a visit to the emergency department might trigger different cost-sharing than an outpatient clinic visit. Check for explicit limits on therapy visits and whether the insurer requires preauthorization for durable medical equipment or extended rehabilitation. A clear read on covered services helps you estimate likely out-of-pocket costs before you commit to a particular course of care.
Look for exclusions and dollar or visit caps in the policy language because they directly affect bills. If a benefit looks missing or capped, consider calling the insurer for clarification before scheduling non-urgent services.
Understand networks, referrals, and prior authorizations
Going out of network can turn a modest bill into a large one, and some plans pay little or nothing for out-of-network providers. Many insurers require a referral or prior authorization for specialty services and certain diagnostics, and skipping that step may lead to claim denials. Emergency care is often treated differently, but follow-up care might require switching to in-network providers to keep costs down. Knowing the steps to secure authorization prevents unpleasant surprises on an explanation of benefits.
Ask your plan how they define emergency visits and whether they will cover follow-up care with out-of-network specialists. Having the insurer confirm this on record is helpful when filing claims.
Document the incident, timeline, and medical records
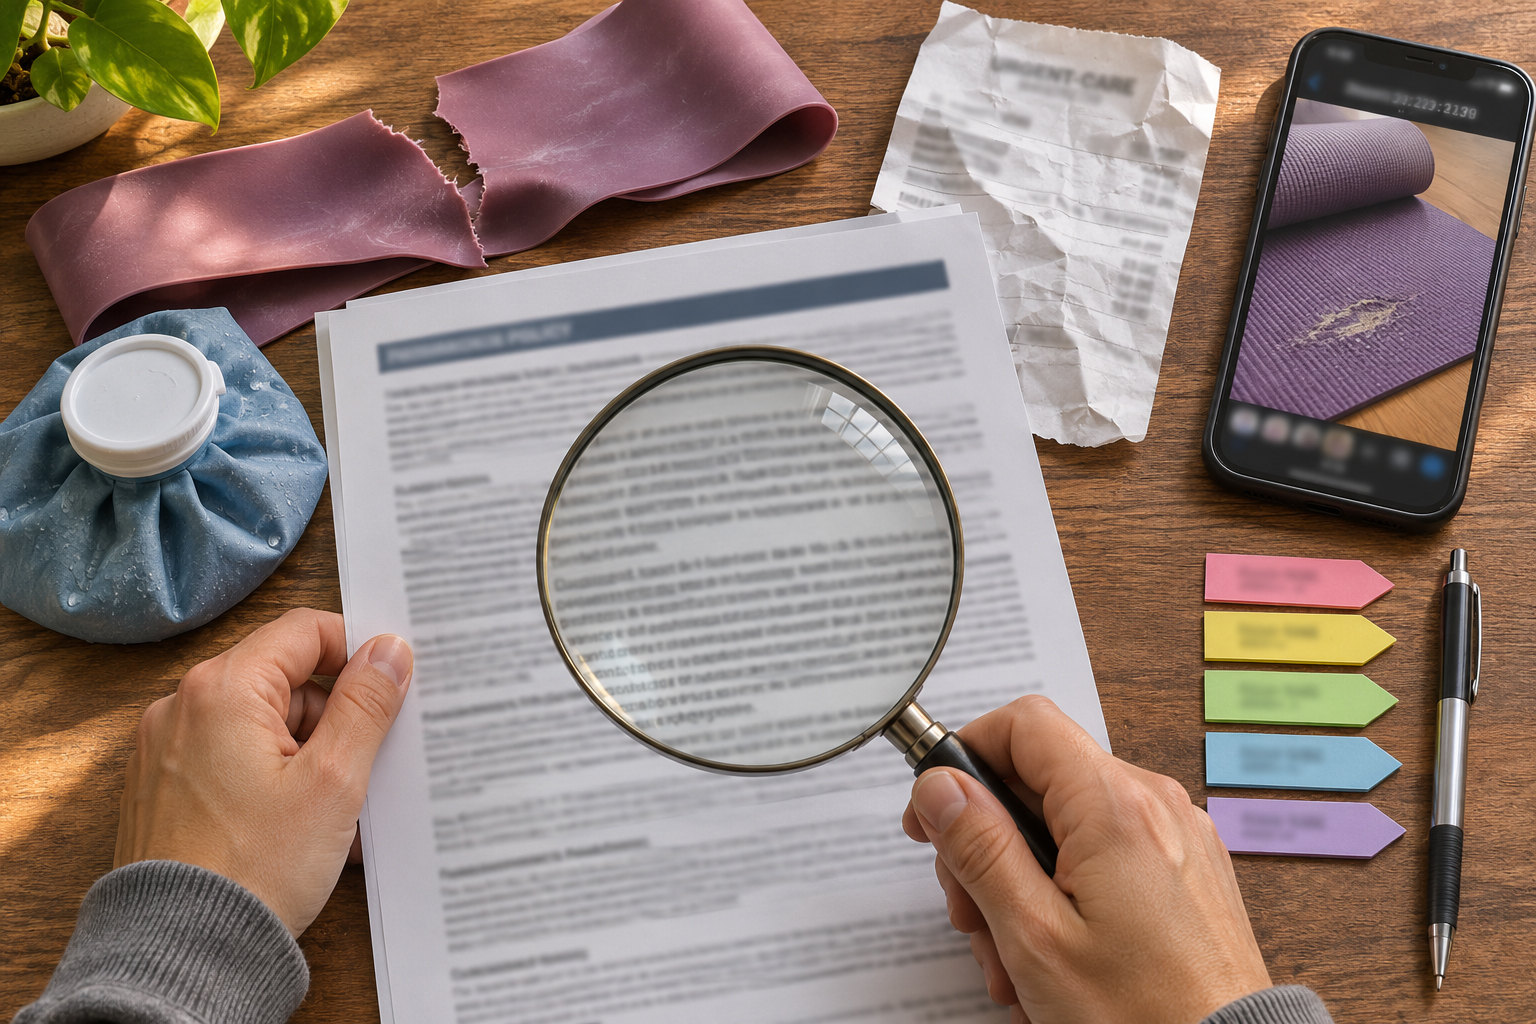
A clear paper trail strengthens any claim and speeds payment decisions, especially when the cause of injury could be disputed. Save appointment notes, receipts, imaging reports, and any correspondence with the insurer, and note dates and times of calls you place. Timely filing matters; many policies set strict deadlines for notification and claims submission that affect coverage. Being organized also makes it easier to appeal a denied claim and to explain circumstances to a claims adjuster.
Keep copies of all records in a single folder and request written summaries from providers when possible. This small investment of time pays off if questions arise during claims processing.
Conclusion
Insurance decisions after a home workout injury often hinge on a few specific policy details, not broad promises. Checking coverage for services, network rules, and documentation requirements before and after care reduces financial risk. A calm, organized approach makes managing bills and claims far less stressful.