<p>When a stretch or a fall during an at-home workout leads to medical care, the path from treatment to reimbursement can feel unclear.
Insurers weigh several factors before approving a claim, and knowing those factors ahead of time reduces stress and surprises.
This article breaks down what underwriters and claims adjusters look for and what you can do to present a strong case.
Read on to learn the practical steps that most consistently help claims succeed.</p>
<h4>What insurers review first</h4>
<p>Insurers begin with the basics: where and when the injury happened, who treated it, and whether the care sought matches the reported problem. They compare your medical records, the provider’s notes, and any eyewitness or incident reports to check for consistency. Prior authorization, policy exclusions, and whether the provider is in-network also influence an early decision. A clear, consistent timeline and credible medical documentation speed up this initial evaluation and reduce the chance of routine follow-ups or requests for more details.</p>
<p>Keep in mind that the first review is not the final word; many claims move forward after an insurer requests clarification or additional records. Respond promptly and provide exactly what’s asked to avoid delays.</p>
<h4>Key documentation that helps claims</h4>
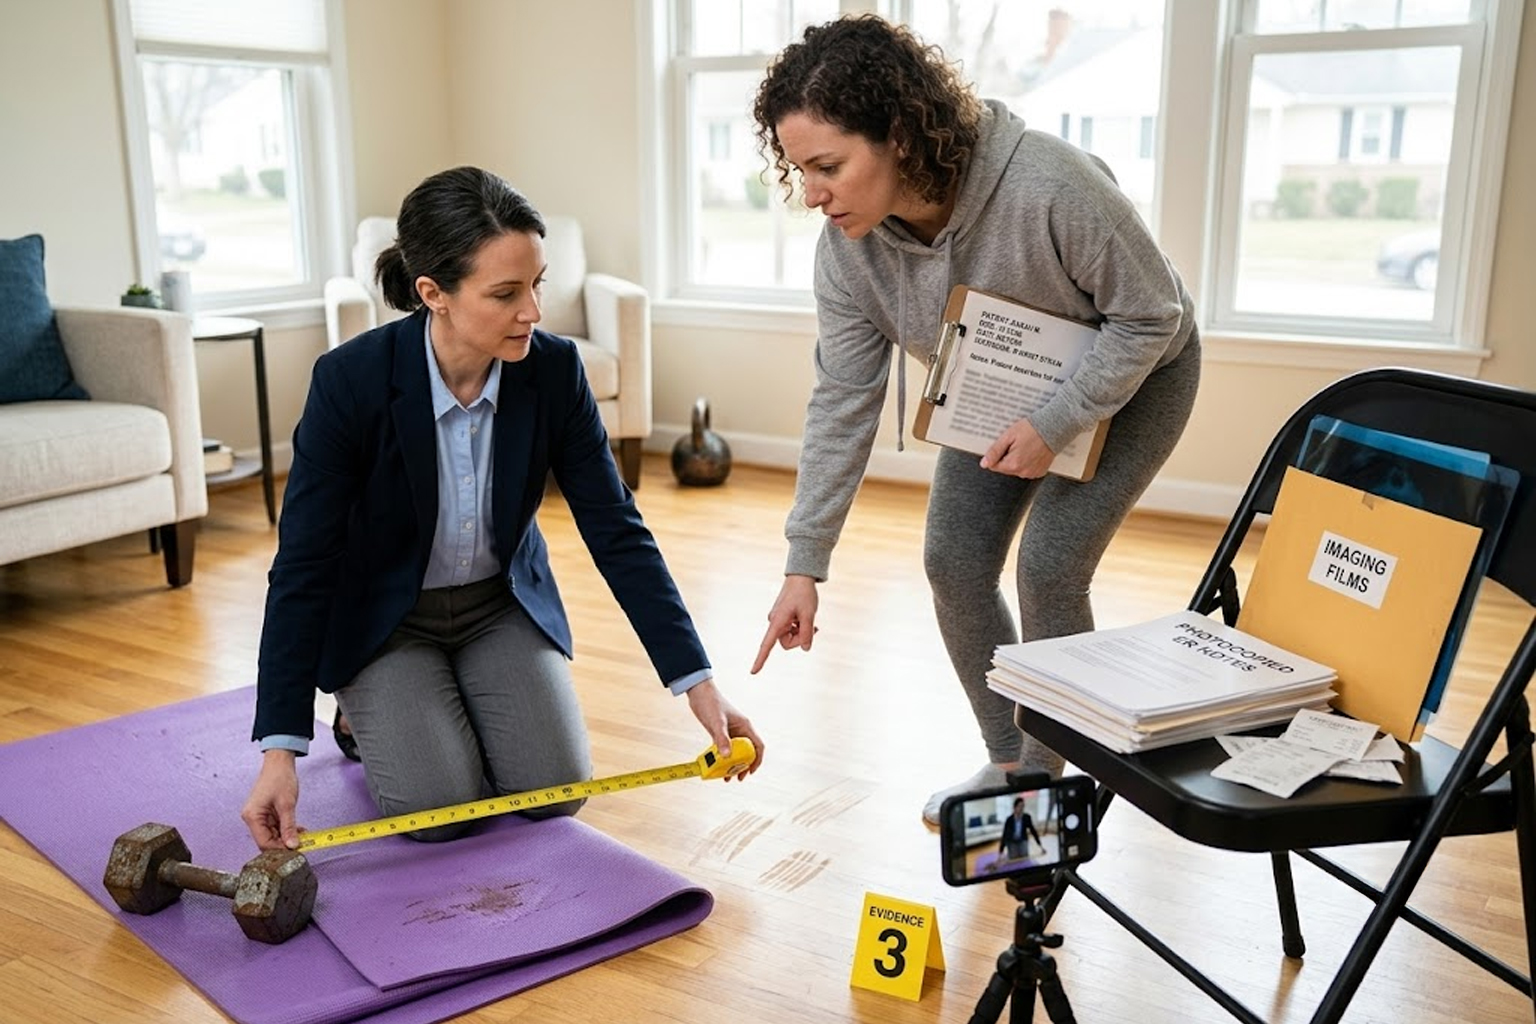
<p>Good records carry disproportionate weight in claim reviews. The most persuasive items are contemporaneous medical notes, emergency or urgent care records, diagnostic imaging reports, and receipts for treatments or supplies. Notes that tie the injury directly to the at-home incident—dates, observed symptoms, and treating clinician impressions—make it easier for examiners to match care to the event. Documentation from any witnesses or household members can be useful when an incident occurred without a third-party report.</p>
<ul><li>Emergency department or urgent care notes</li><li>Imaging and test reports (X-ray, MRI)</li><li>Provider progress notes and treatment plans</li><li>Photographs of injuries or scene, when relevant</li></ul>
<p>Organize these items chronologically and submit copies, not originals, unless the insurer requests otherwise. A neat packet helps reviewers and shortens processing time.</p>
<h4>Common reasons claims are denied</h4>
<p>Denials often stem from documentation gaps, late reporting, or exclusions in the policy such as pre-existing conditions. Insurers may also deny coverage if care appears elective or unrelated to the reported injury. Inconsistent statements between your claim form and medical notes raise red flags and invite closer scrutiny. Understanding the specific exclusion language in your policy—like sports-related clauses or limits on home-based activities—lets you anticipate pushback.</p>
<ul><li>Missing or vague medical records</li><li>Policy exclusions or lack of coverage for a specific treatment</li><li>Late filing or missed authorization steps</li></ul>
<p>If a claim is denied, request a clear explanation in writing and ask how to appeal. Many denials are reversible with additional documentation or clarification.</p>
<h4>Practical steps to strengthen a claim</h4>
<p>Act quickly: seek medical care, get written records, and report the incident to your insurer per policy timelines. Take photos, collect witness statements, and keep receipts for any out-of-pocket costs. Ask your treating clinician to note the cause of injury in their records and to outline the recommended follow-up care. If a referral or prior authorization is required, secure it before non-emergency treatment whenever possible.</p>
<ul><li>Report the incident promptly to your insurer</li><li>Request copies of all medical records and imaging</li><li>Follow prescribed care and keep appointment notes</li></ul>
<p>Clear, timely action makes the difference. Preparation and organized paperwork improve both processing time and the odds of approval.</p>
<h4>Conclusion</h4>
<p>Insurers focus on timing, consistency, and credible medical evidence when reviewing at-home exercise claims.
Organize records, act promptly, and understand your policy’s exclusions to reduce surprises.
If denied, follow the insurer’s appeal steps and submit any additional documentation quickly.</p>