When you exercise at home the risk of an injury is usually low but not zero, and understanding your insurance limits matters. Reviewing deductibles, co-insurance, and annual out-of-pocket maximums can change how you plan recovery and care. This article explains practical steps to interpret those limits and anticipate potential costs. It aims to help home exercisers make informed decisions about coverage and care.
Coverage basics to review
Start by identifying what your health plan categorizes as an injury and which services are covered for treatment, from urgent care visits to physical therapy. Look for exclusions related to self-inflicted injuries or activities deemed high risk, and note provider network requirements that may affect costs. Understand whether telehealth or virtual physiotherapy sessions are included, since at-home treatment options can reduce expenses. Clarifying these basics helps you predict where limits and copays will apply.
Once you know the definitions and network rules, you can estimate how much a common treatment pathway might cost. Put key numbers in a simple comparison to weigh plan options more clearly.
Documenting incidents and preparing claims
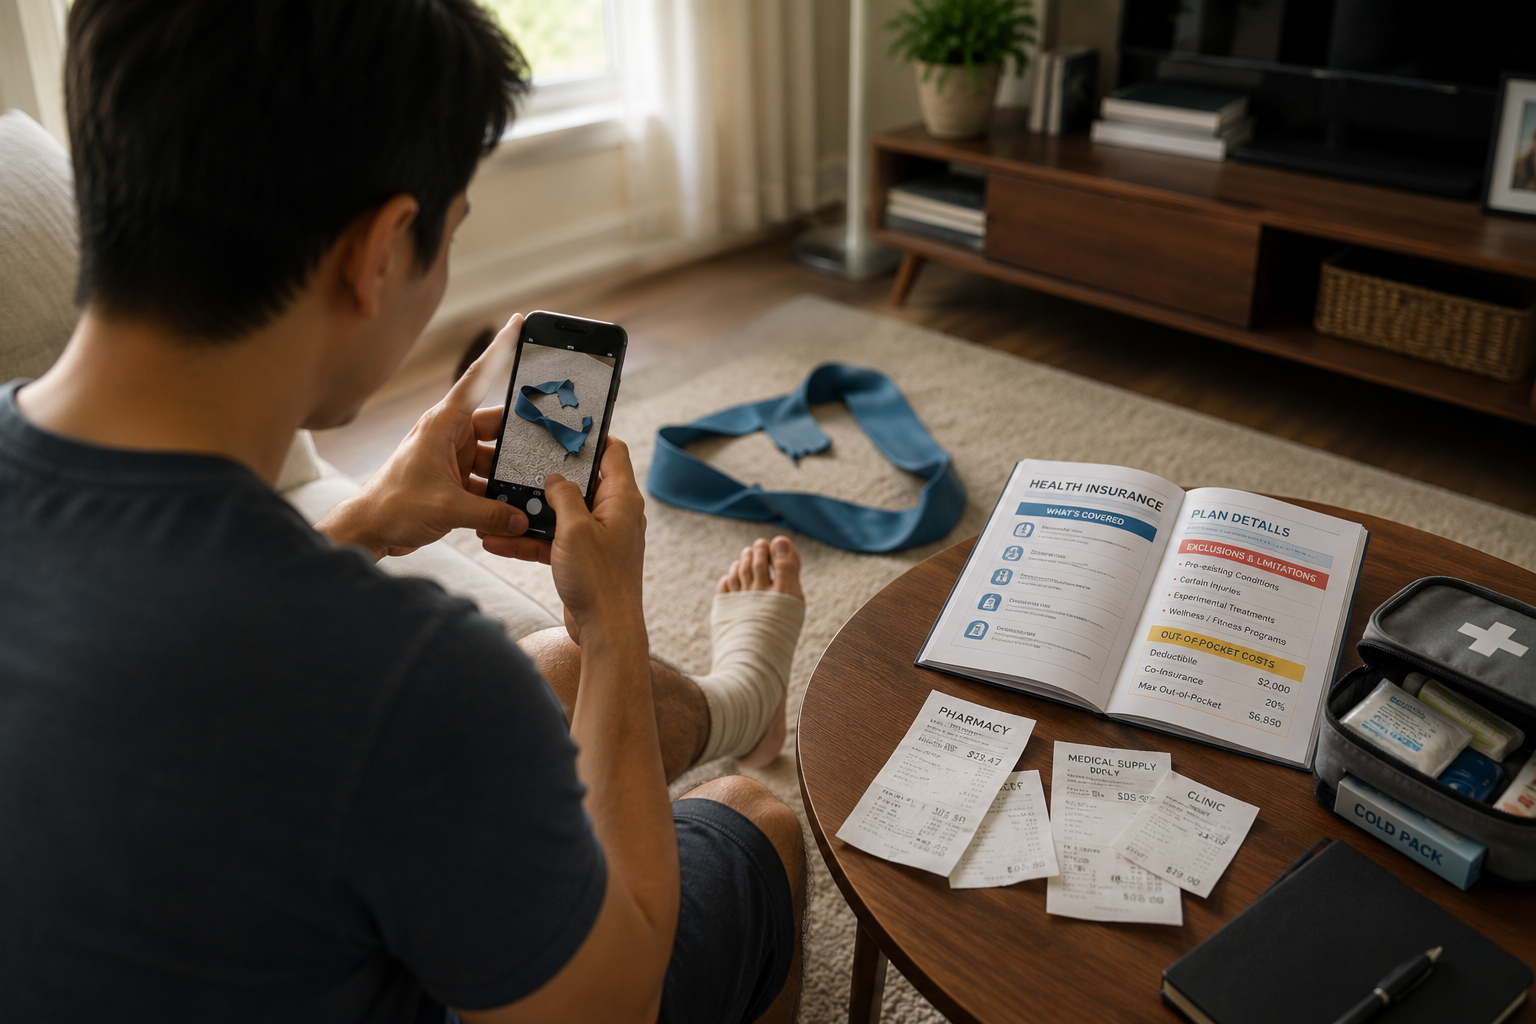
Accurate documentation makes claims smoother: record the incident date, pain onset, and any immediate care you received. Keep receipts for appointments, invoices for imaging or therapy, and notes from clinicians describing diagnosis and recommended treatment. Photograph the scene or equipment if it contributed to the injury, and retain any workout logs that demonstrate routine rather than reckless behavior. Organized records speed up insurer review and reduce the chance of denials based on missing information.
Report the incident promptly according to your plan’s claims timeline and follow up with written summaries when required. Consistent documentation can improve the likelihood of appropriate coverage.
Managing out-of-pocket exposure
To limit unexpected costs, explore options such as choosing in-network providers, asking for bundled physical therapy sessions, and requesting prior authorization for non-routine services. Compare estimated costs of care against your deductible to determine whether you’ll reach key thresholds that change insurer responsibility. Consider short-term measures like urgent care for initial evaluation instead of emergency department visits when appropriate. Small choices before and during care often influence total financial exposure.
Additionally, review whether supplemental plans or health savings accounts can be used for copays and deductibles. These measures provide flexible ways to ease out-of-pocket burdens without changing primary coverage.
Conclusion
Knowing your plan’s limits and likely out-of-pocket costs helps you make smarter decisions about care after a home workout injury. Clear documentation, choosing in-network care, and using available cost-saving tools reduce financial surprises. Regularly reviewing your policy ensures you stay prepared as your fitness routine evolves.