A sprain or fall during a session in your living room can lead to more than soreness.
Understanding how your health plan responds will help you avoid surprise bills.
This article walks through the insurance steps to take if a home workout leads to medical care.
Read these practical checks before you set up equipment or chase a new personal best.
Know what your policy actually covers
Start by reviewing key sections of your policy: emergency care, urgent care, outpatient services, and rehabilitation benefits. Pay attention to in-network versus out-of-network rules, deductibles, and any prior-authorization requirements for imaging or physical therapy. Some plans treat telehealth or virtual rehab differently, while others limit coverage for non-emergency injuries that occur at home. Understanding these distinctions reduces the chance of unexpected out-of-pocket costs.
Call your insurer with specific questions and document the answers you receive, including date, agent name, and confirmation numbers. That record can be invaluable if a claim is disputed later.
Immediate actions after an injury
If you need urgent care, choose the level of care that fits the injury: telehealth for minor strains, urgent care for moderate issues, and emergency care for serious trauma. Ask the provider to note how the injury happened and to include clear diagnostic codes on all paperwork. Collect receipts, itemized bills, and visit notes at the time of service to speed the claims process. Early documentation makes it easier to show medical necessity if the insurer requests justification.
Keep digital copies of medical records and bills, and request electronic Explanation of Benefits (EOB) statements from your insurer. These files are the backbone of any claim or appeal.
Rehab, physical therapy, and follow-up care
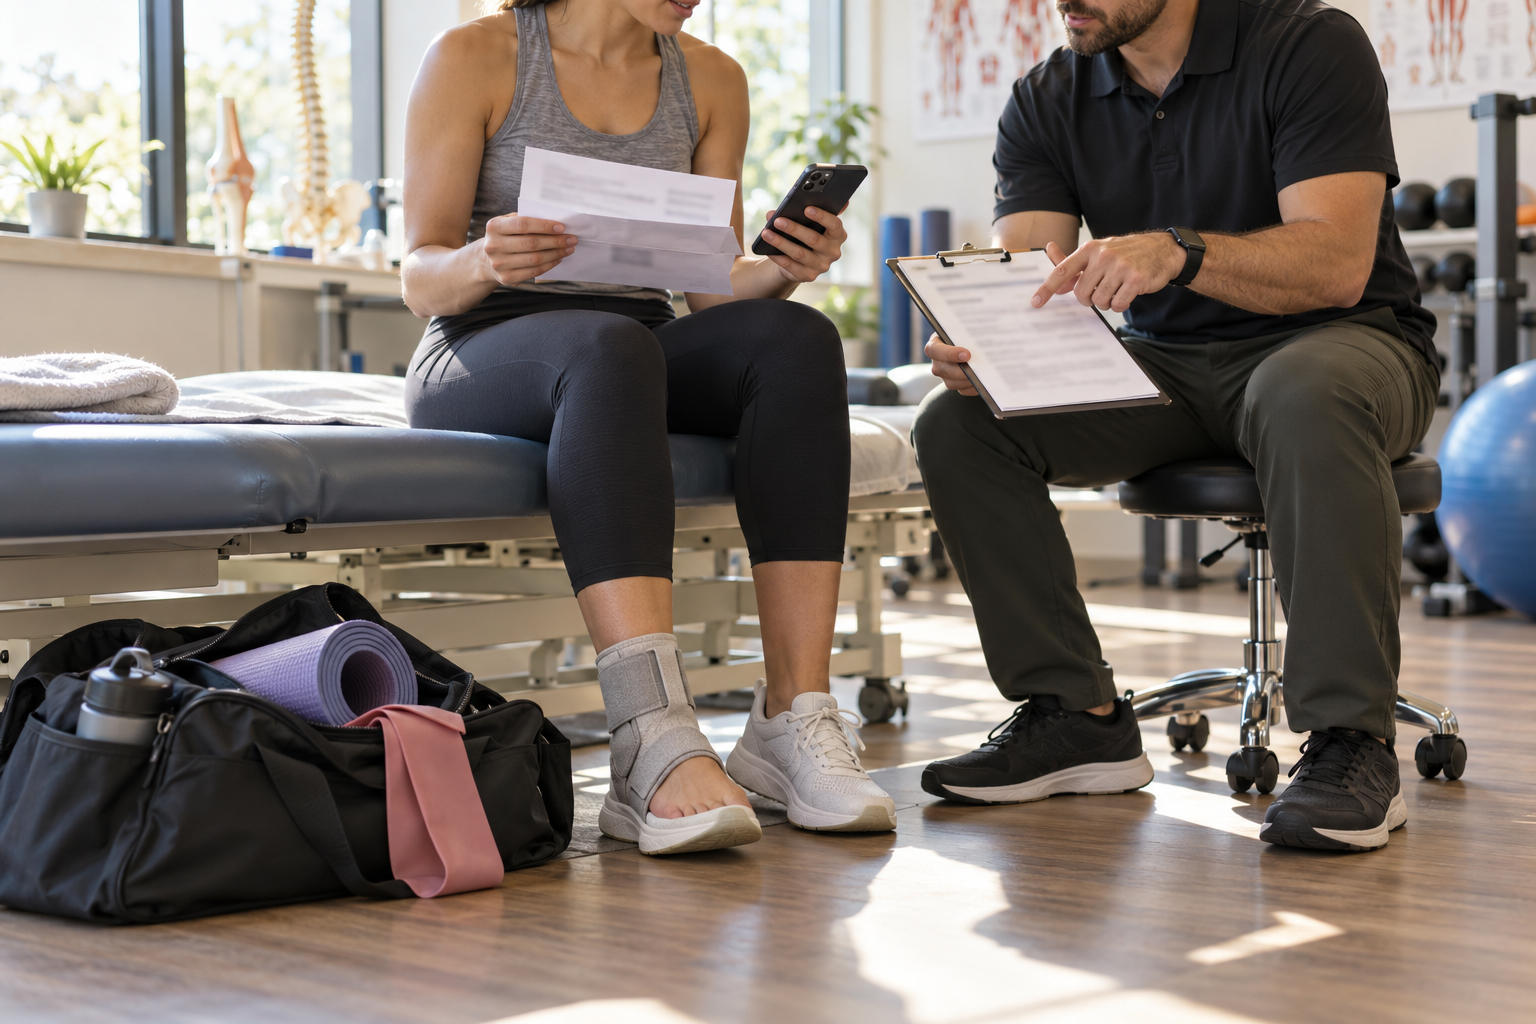
Recovery from a workout injury often requires follow-up visits and physical therapy, and coverage varies widely for these services. Check visit limits, co-insurance rates, and whether a referral or preauthorization is required for PT or specialty appointments. If your preferred therapist is out-of-network, ask about gaining in-network approval or whether your plan offers any out-of-network reimbursement. Also confirm whether tele-rehab sessions count toward your benefit limits.
Compare providers and get authorization in writing when possible to avoid surprise bills once rehab is underway. Small administrative steps up front can prevent larger costs down the road.
Filing claims, denials, and appeals
When you submit a claim, include all supporting documentation: provider notes, incident details, receipts, and any insurer confirmations you recorded. If a claim is denied, review the denial reason and the plan’s appeal process and deadlines carefully. Prepare a concise appeal with medical records and a letter from your treating provider explaining necessity. If an internal appeal fails, you usually have the option to escalate to external review or contact your state insurance regulator for guidance.
Maintain an organized folder of every communication and document to strengthen appeals and shorten resolution time. Persistence and clear evidence often turn a denial into a paid claim.
Conclusion
Check your policy specifics before you outfit a home gym and know how to document any injury.
Act promptly after an incident: seek appropriate care, collect records, and contact your insurer.
With clear records and timely steps you can limit surprises and protect your finances while staying active.