As more people build consistent fitness routines at home, understanding how medical insurance intersects with those activities becomes increasingly important. Home workouts lower barriers to exercise but introduce different risks and documentation needs compared with gym-based training. This article outlines key policy features to review, practical steps to document incidents, and options that can bridge coverage gaps for home-based exercisers. Read on to make informed choices that support safety and financial preparedness around your fitness routine.
Understanding core coverage elements
Begin by checking what your plan covers for emergency care, urgent care, and outpatient services that might follow an exercise-related injury. Look for clear language on rehabilitation services such as physical therapy, durable medical equipment, and diagnostic imaging. Verify whether pre-authorization or network restrictions apply to certain providers, since these rules affect costs and access. Knowing these basics helps you estimate out-of-pocket exposure if an injury requires follow-up care.
Also confirm how exclusions or limitations are applied to injuries sustained during recreational or self-directed exercise. Ask your insurer about common scenarios to avoid surprises after a claim. Having clarity up front reduces stress if you need to file a claim.
Documenting workouts, incidents, and expenses
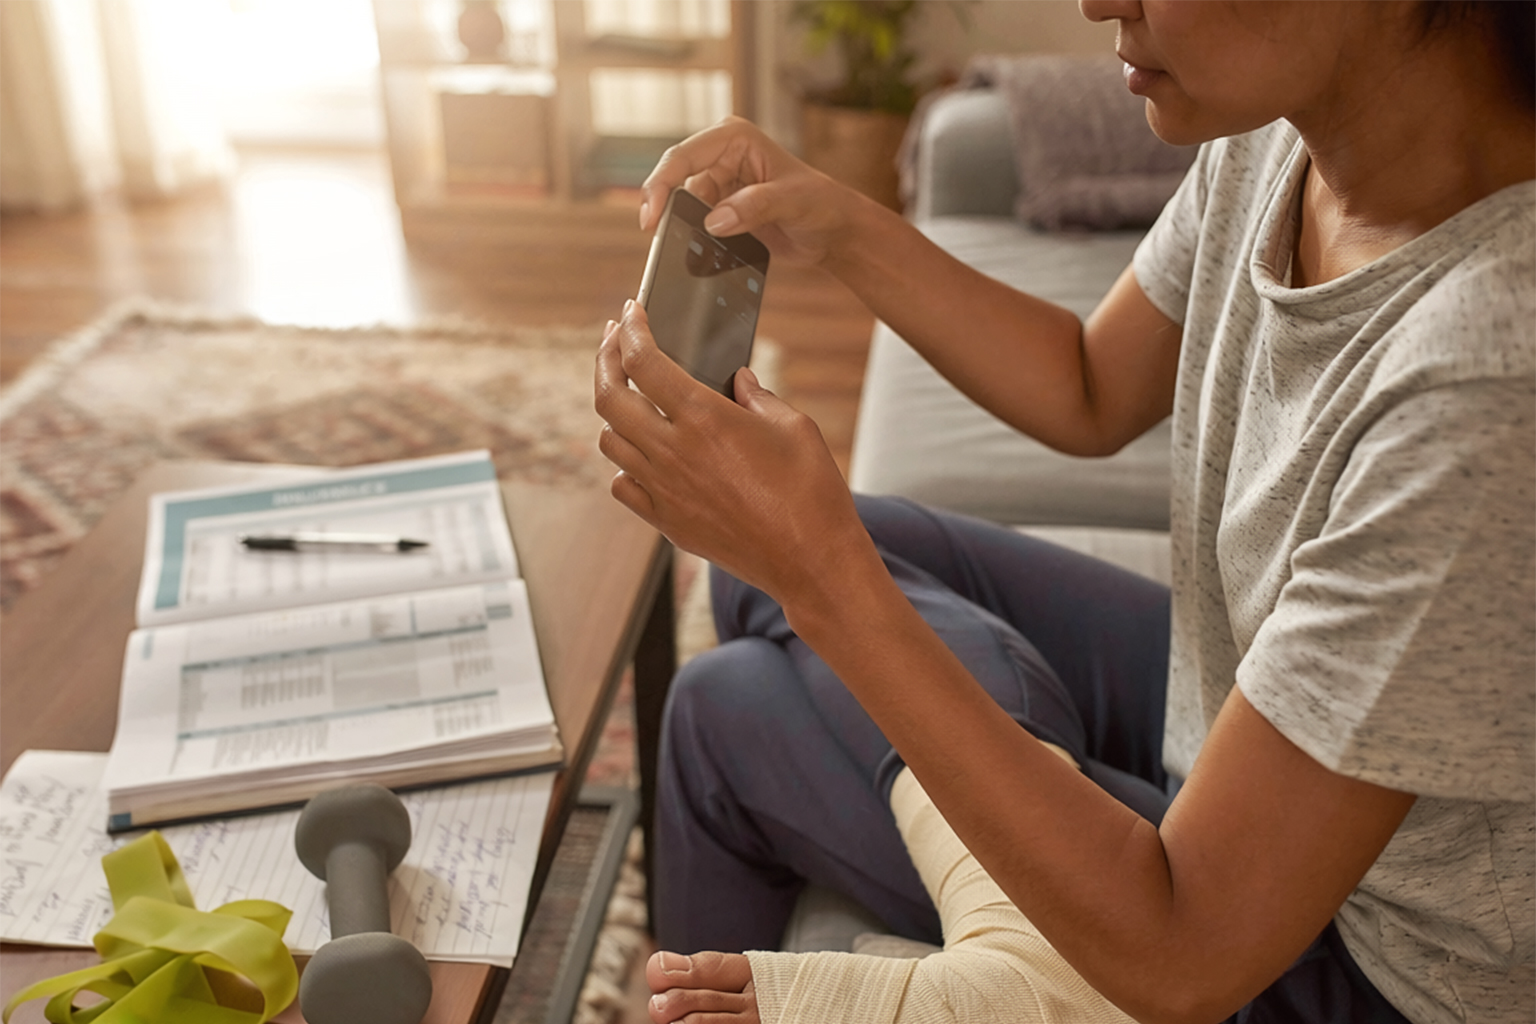
Accurate documentation strengthens a claim and clarifies causation when an injury occurs at home. Keep a concise incident log noting date, time, activity, location, and any witnesses, and retain photos of the scene and any visible injury. Save receipts for equipment, repairs, telehealth visits, and any over-the-counter supplies used as part of recovery. Medical records should explicitly link your treatment to the incident to support coverage for related services.
Timely documentation is especially important if a claim is contested or if your plan has strict notification windows. Maintain both digital and physical copies to ensure nothing gets lost.
Using preventive benefits and telehealth options
Many plans include preventive services, wellness visits, and virtual consultations that can help you avoid injury or address minor issues before they escalate. Virtual physical therapy and remote follow-ups are increasingly covered and can be convenient after a home workout mishap. Check whether telehealth providers require in-network status or follow-up with in-person care to maintain full coverage. Preventive benefits often reduce overall costs by catching problems early.
Leverage these services to stay proactive about mobility, form correction, and gradual progression in your routine. Early professional input can prevent small setbacks from becoming major interventions.
Supplemental policies and cost considerations
If gaps remain, explore supplemental options such as short-term accident policies, riders for outpatient therapy, or flexible spending arrangements that offset co-pays and deductibles. Balance premium increases against likely benefits by estimating how often you may need care related to home exercise. Read policy language about exclusions, waiting periods, and claim limits to ensure the add-on delivers real value.
- Accident riders can help with unexpected injury expenses.
- Health savings accounts offer tax-advantaged ways to pay deductibles.
- Short-term policies may cover high-deductible gaps for specific activities.
Always compare total annual costs, not just monthly premiums, before adding coverage. Small supplemental choices can provide peace of mind without excessive expense.
Conclusion
Review policy details, document activity and incidents carefully, and use preventive and telehealth benefits to reduce risk. Consider targeted supplements only after weighing costs and exclusions. Being informed lets you enjoy home fitness with better protection and fewer surprises.