Arranging medical care at home can save time and help recovery, but insurance rules vary widely. Before a provider arrives, understand what services and equipment your plan treats as medically necessary. A little paperwork and a clear treatment rationale often separate a covered visit from an unexpected bill. This article outlines practical steps to prepare claims, track expenses, and handle denials.
Understand what insurers commonly cover
Most plans distinguish between medical care and general wellness. They are likelier to cover skilled nursing, physical therapy, durable medical equipment, and certain home health aides when there is a physician’s order. Routine fitness equipment or long-term companionship typically falls outside coverage unless tied to a documented medical need. Review your plan’s summary of benefits to find definitions and coverage limits before scheduling services. Also check for annual caps and rental versus purchase rules for equipment.
Knowing the covered categories helps set realistic expectations and avoids surprise bills. If something is unclear, ask your plan for a written policy statement. Keep a simple folder or digital file to find paperwork quickly.
Documentation and billing tips that help claims succeed
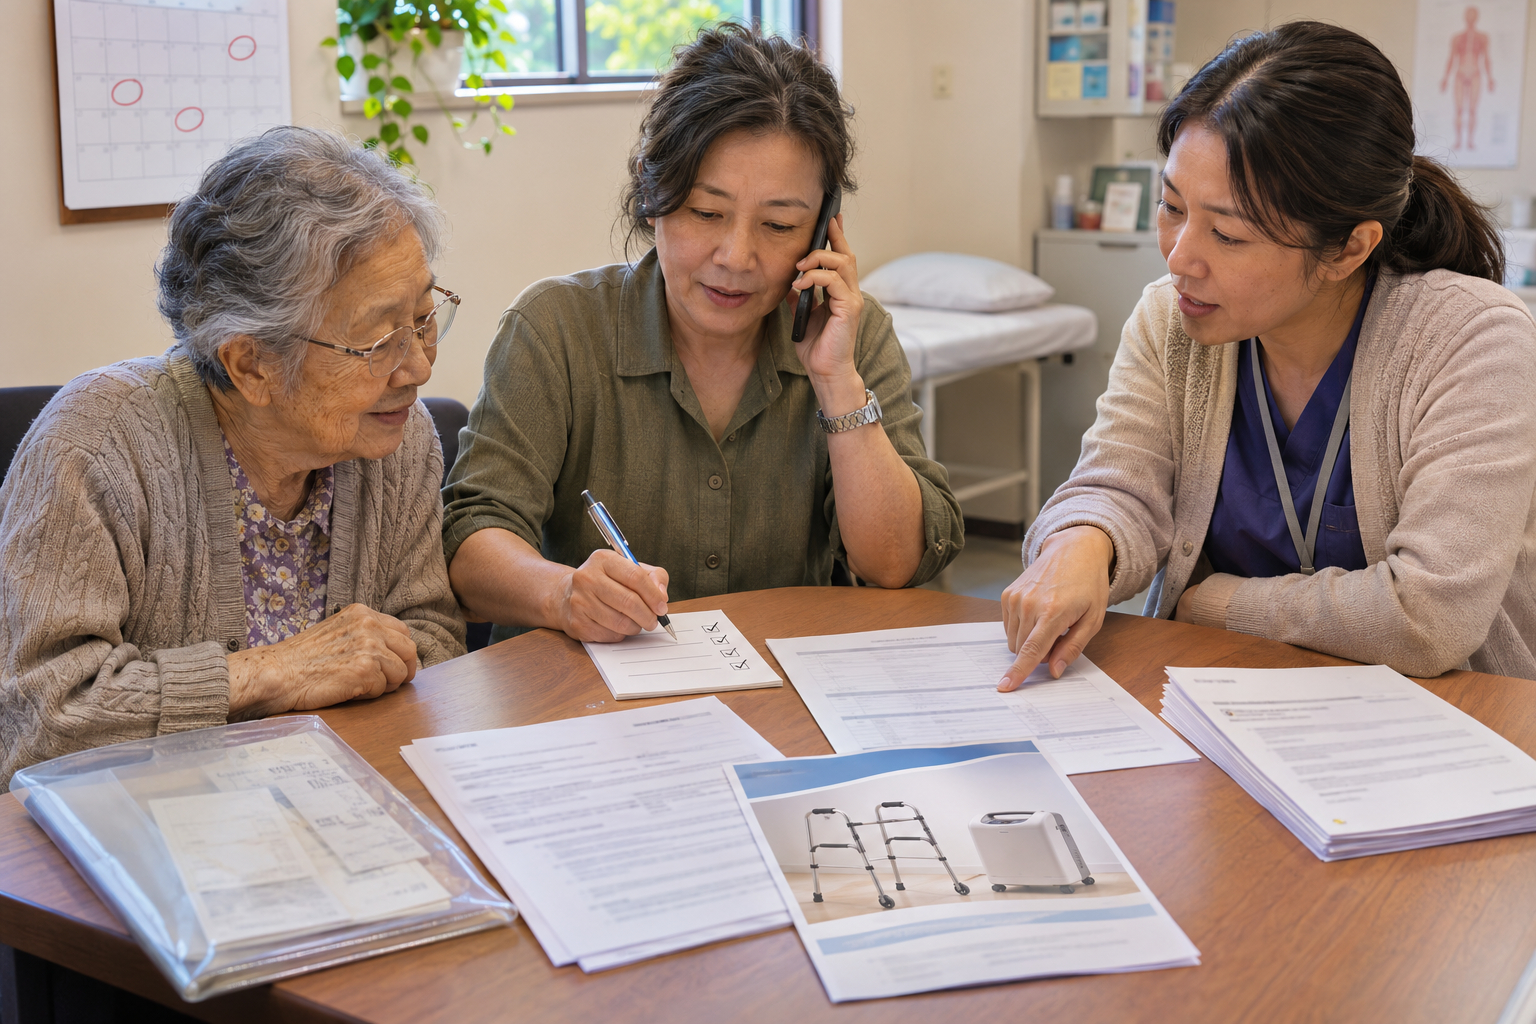
Insurers want clinical justification. Make sure any home service has a physician’s order that specifies diagnosis, frequency, and measurable goals. Keep copies of progress notes, therapy plans, and receipts for equipment that is billed as durable medical equipment. Confirm that providers use correct billing codes and submit to the insurer before requesting patient payment. If possible, get prior authorization in writing before services begin to avoid denials.
A short checklist—physician order, detailed invoice, medical notes—goes a long way. Send photocopies, not originals, and log dates you submitted each document. Follow up with the insurer by phone and note names and dates.
When to appeal and how to ask for exceptions
If a claim is denied, read the denial letter carefully; it must explain why and how to appeal. Gather supporting medical records, letters from treating clinicians, and any prior authorization approvals to build your case. Many plans allow an internal appeal followed by an external review if the insurer still denies coverage. Time limits matter — appeals often must be filed within 30 to 180 days. If you receive an adverse decision, ask for the clinical criteria the insurer used.
If costs remain high, discuss payment plans with providers while the appeal is pending. You can also request an expedited review for urgent situations. Seek help from patient advocates or a case manager at the provider if you need assistance.
Conclusion
Start early and keep records. Speak directly with the insurer and care provider. Document everything and ask for written decisions.