When you exercise regularly outside of a commercial gym, your medical coverage should reflect the types of care you might need.
A thoughtful plan balances access to urgent care, rehabilitative services, and telehealth consultations with an eye toward predictable out-of-pocket costs.
Reviewing benefits, exclusions, and provider networks before an incident reduces stress and bills when treatment is required.
This guide outlines practical steps to match a policy to active personal routines and to manage claims efficiently.
Assess Policy Basics
Start by identifying core benefit elements: deductible, copay, coinsurance, out-of-pocket maximum, and whether the plan favors in-network providers.
Confirm how the plan covers emergency visits, urgent care, physical therapy, imaging, and telehealth, since these services often follow acute workout injuries.
Pay attention to prior authorization rules for rehabilitation or specialist referrals and any limits on therapy visits per injury.
Also check exclusions such as treatment for certain recreational or high-risk activities that could affect a claim.
Summarize these findings in a one-page comparison for any plans you consider.
That reference makes it easier to choose or to raise targeted questions with an agent or the insurer.
Documenting Injury and Care
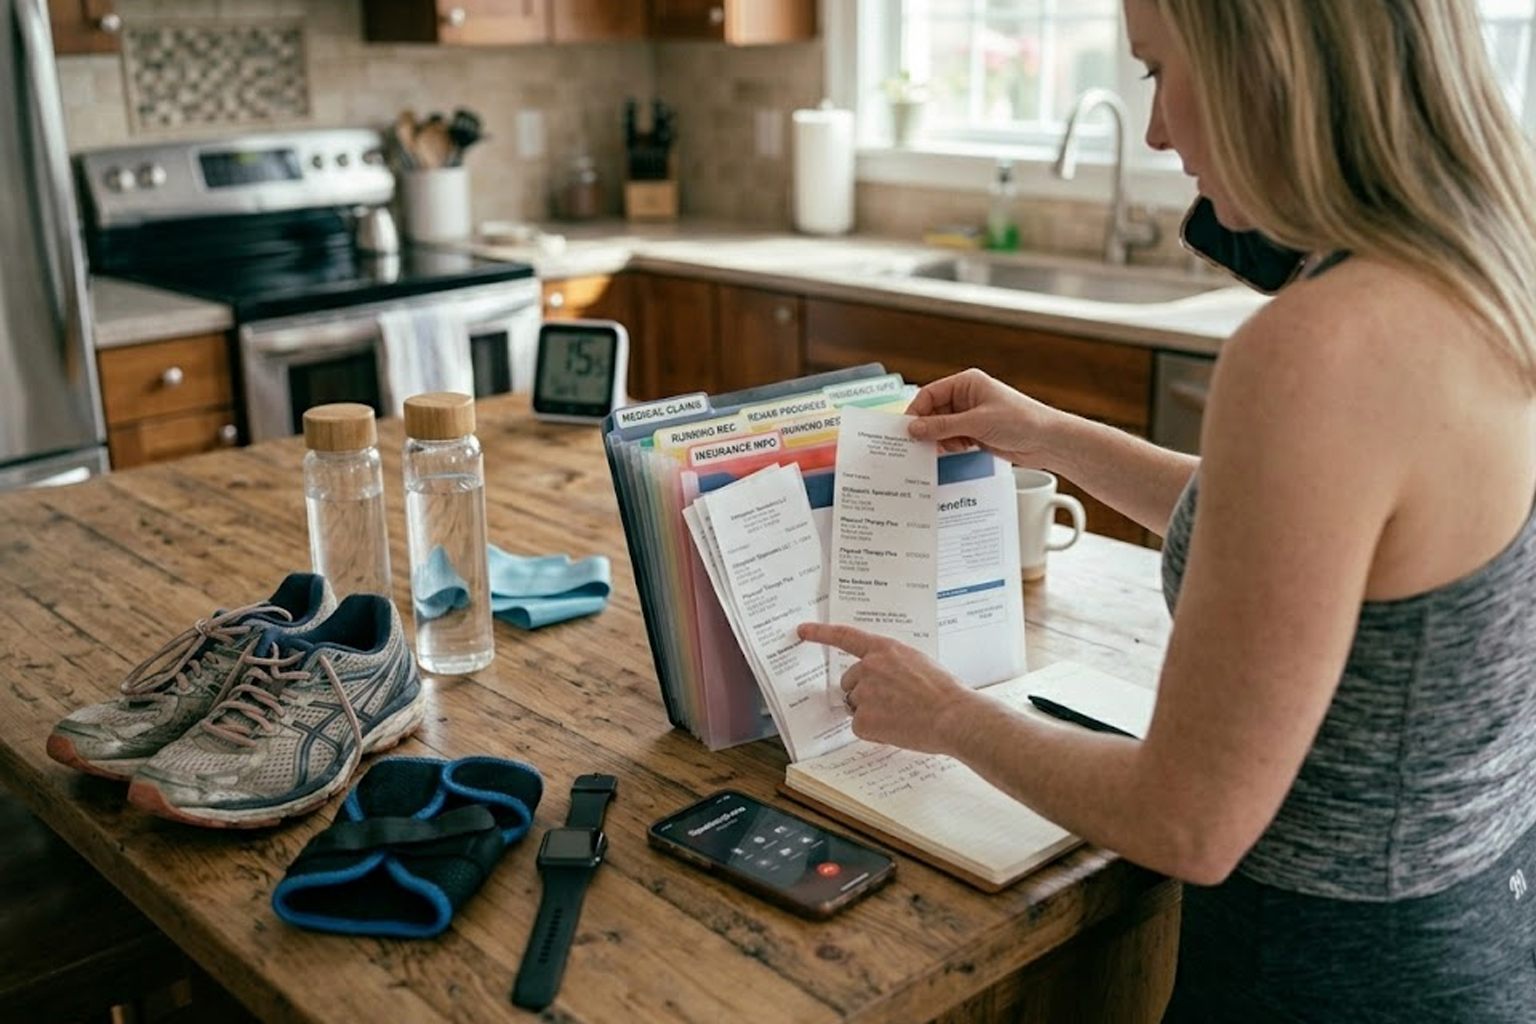
When an injury occurs, comprehensive documentation improves claim outcomes and speeds appeals if needed.
Collect timely records: event description, timestamps, photos of the scene and injuries, and receipts for care or equipment repairs.
Ask treating providers for clear diagnoses, treatment plans, and progress notes that link care to the incident.
Digital activity logs from wearables or apps can also corroborate timelines and intensity of activity.
- Incident description and photos
- Provider notes and bills
- Receipts and activity logs
Organize records in a single folder and copy relevant documents when filing a claim.
Prompt submission and polite, factual communication with the insurer reduce processing delays.
Manage Costs and Provider Choices
Cost management starts with choosing the deductible and copay structure that suits your care patterns.
If you rarely visit clinicians, a higher deductible plan paired with a health savings account may lower premiums while preserving access.
For frequent therapy or specialist needs, prefer plans with stronger in-network coverage or lower cost-sharing for rehabilitative services.
Where possible, use in-network providers, transparent pricing tools, and telehealth to limit unexpected balances.
Negotiate bills and request itemized statements if charges seem incorrect.
Consider supplemental riders or short-term coverage for planned procedures tied to training or recovery.
Conclusion
Proactive policy review and organized documentation create a smoother path from injury to recovery.
Understand service limits, provider rules, and claims timelines before you need them.
That preparation keeps attention on healing and training, not on paperwork and surprise expenses.