When a home workout turns into a medical bill, more than one insurance policy can sometimes apply. You might have a primary health plan, a spouse’s plan, or a homeowner’s policy that contributes for a guest’s injury. Understanding how those pieces fit can lower your out-of-pocket costs and speed up resolution. This short guide explains why coordination matters and how to approach multiple carriers.
When Multiple Policies Might Apply
If you or an injured guest have separate plans, insurers use rules to decide who pays first. Primary coverage typically pays up to its limits, then secondary coverage may cover remaining eligible costs. Homeowner or renter policies sometimes offer liability coverage for guests hurt by equipment, which can offset medical expenses. Knowing which policy is primary can prevent duplicate claims and denied payments later. Collecting policy numbers and provider contacts early makes coordination smoother.
Start by documenting the injury and getting initial medical care; that creates the claim foundation for every insurer involved. Sharing consistent details with each company reduces discrepancies during claims review.
Order of Benefit Responsibility
Insurers follow an order of benefit rules to avoid paying twice for the same expense. Coordination of benefits (COB) provisions spell out whether an individual’s own plan pays first or whether a spouse’s policy takes precedence. If a liability policy applies, it may be treated differently and require a separate claim. Ask each insurer how they apply COB so you can file with the correct carrier in the right sequence. Mistiming a claim can slow payments and trigger additional paperwork.
Request written confirmation of the payment responsibility from the first payer, then share it with the secondary insurer to speed processing. Keep a running log of claim numbers and contacts as you go.
Common Pitfalls to Avoid
People often assume all policies will split costs automatically, but insurers expect claimants to report other coverage. Failing to disclose a secondary plan can lead to denials or later repayment demands. Another frequent mistake is mixing billing codes or inconsistent injury descriptions between providers and insurers. Also watch for coordination gaps where a liability policy covers only certain expenses while your health plan covers the rest. Clear, consistent records prevent these avoidable problems.
Double-check explanations of benefits (EOBs) from each insurer against your bills to catch errors early. If something looks off, call the claims adjuster right away.
Practical Steps to Coordinate Claims
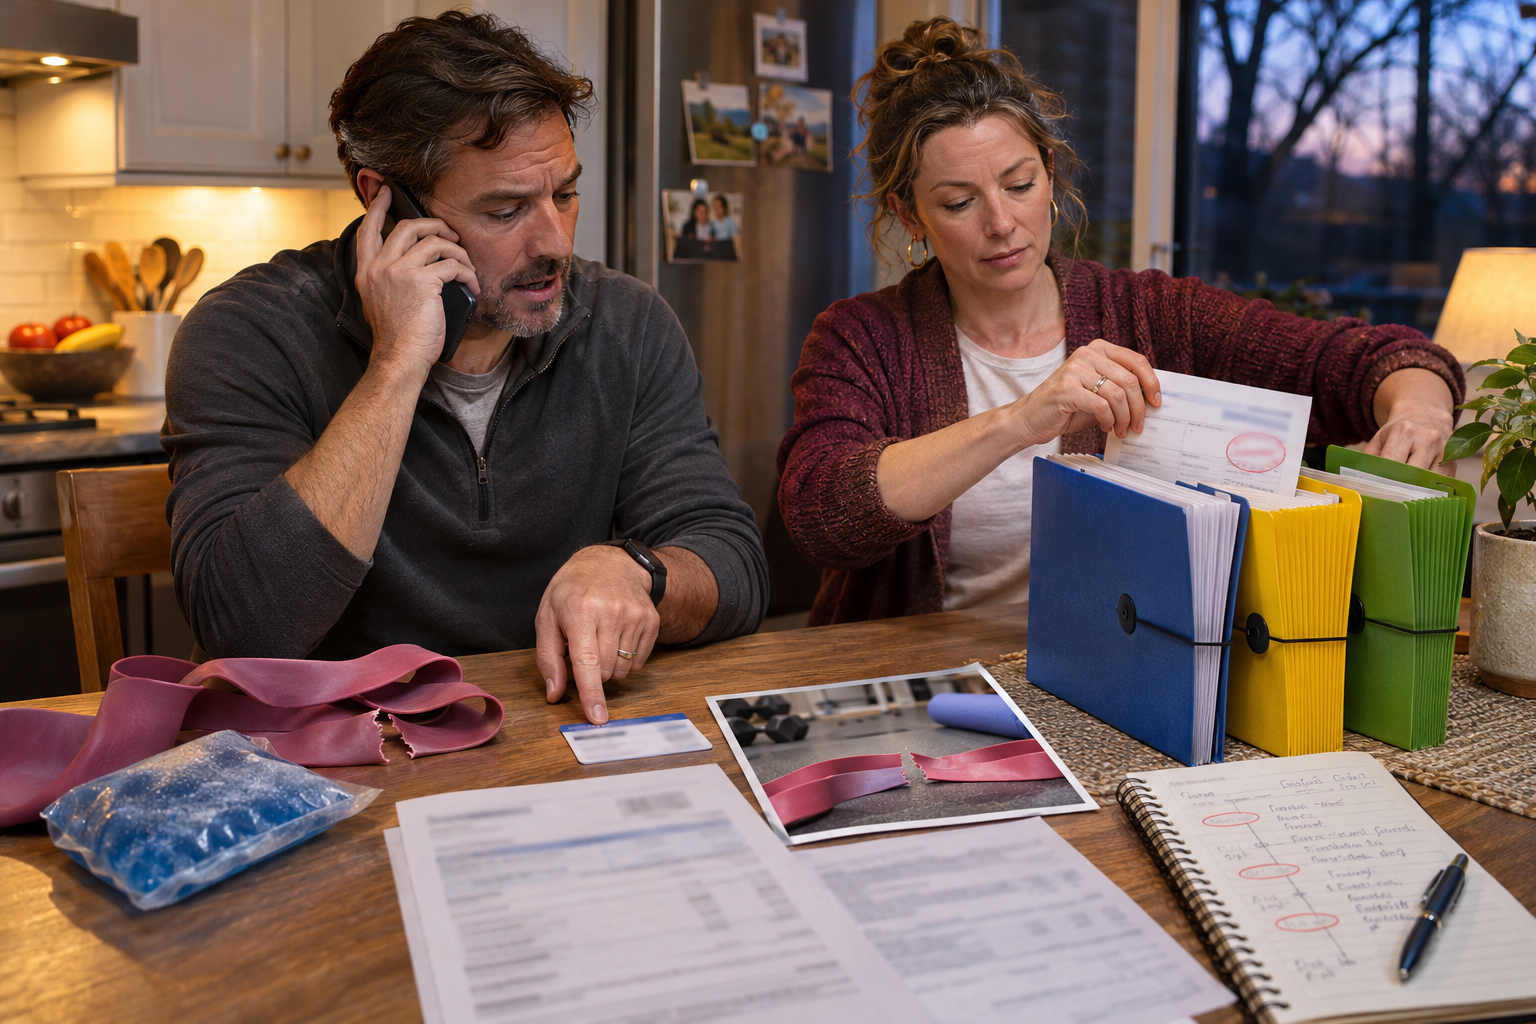
Begin by collecting policy details, claim contacts, and the treating provider’s notes. Notify each insurer promptly and ask who they require as the primary payer, and whether they need an authorization or lien. Provide identical documentation to every carrier: the same date, diagnosis, and treatment notes. Track timelines for claim decisions and appeal deadlines so you don’t miss opportunities to contest denials. If liability coverage is involved, inform your homeowner insurer and get their claim number as soon as possible.
Organize a folder—digital or physical—with all correspondence, bills, and EOBs to make follow-up efficient. When in doubt, request written confirmations from insurers about next steps.
Conclusion
Coordinating multiple policies takes patience and clear documentation. Keep every insurer informed and verify the order of payment before expecting reimbursements. A disciplined paper trail and timely communication will reduce surprises and help settle bills more quickly.