After a home workout leads to medical care, the Explanation of Benefits (EOB) arriving in the mail can feel like a second injury: confusing and unexpected. An EOB is not a bill, but it explains how your insurer processed a claim and what portion may land on your desk. Knowing how to read its line items helps you spot errors, avoid overpaying, and decide whether to appeal. This short guide breaks down the EOB into clear parts and practical next steps.
What an EOB Actually Shows
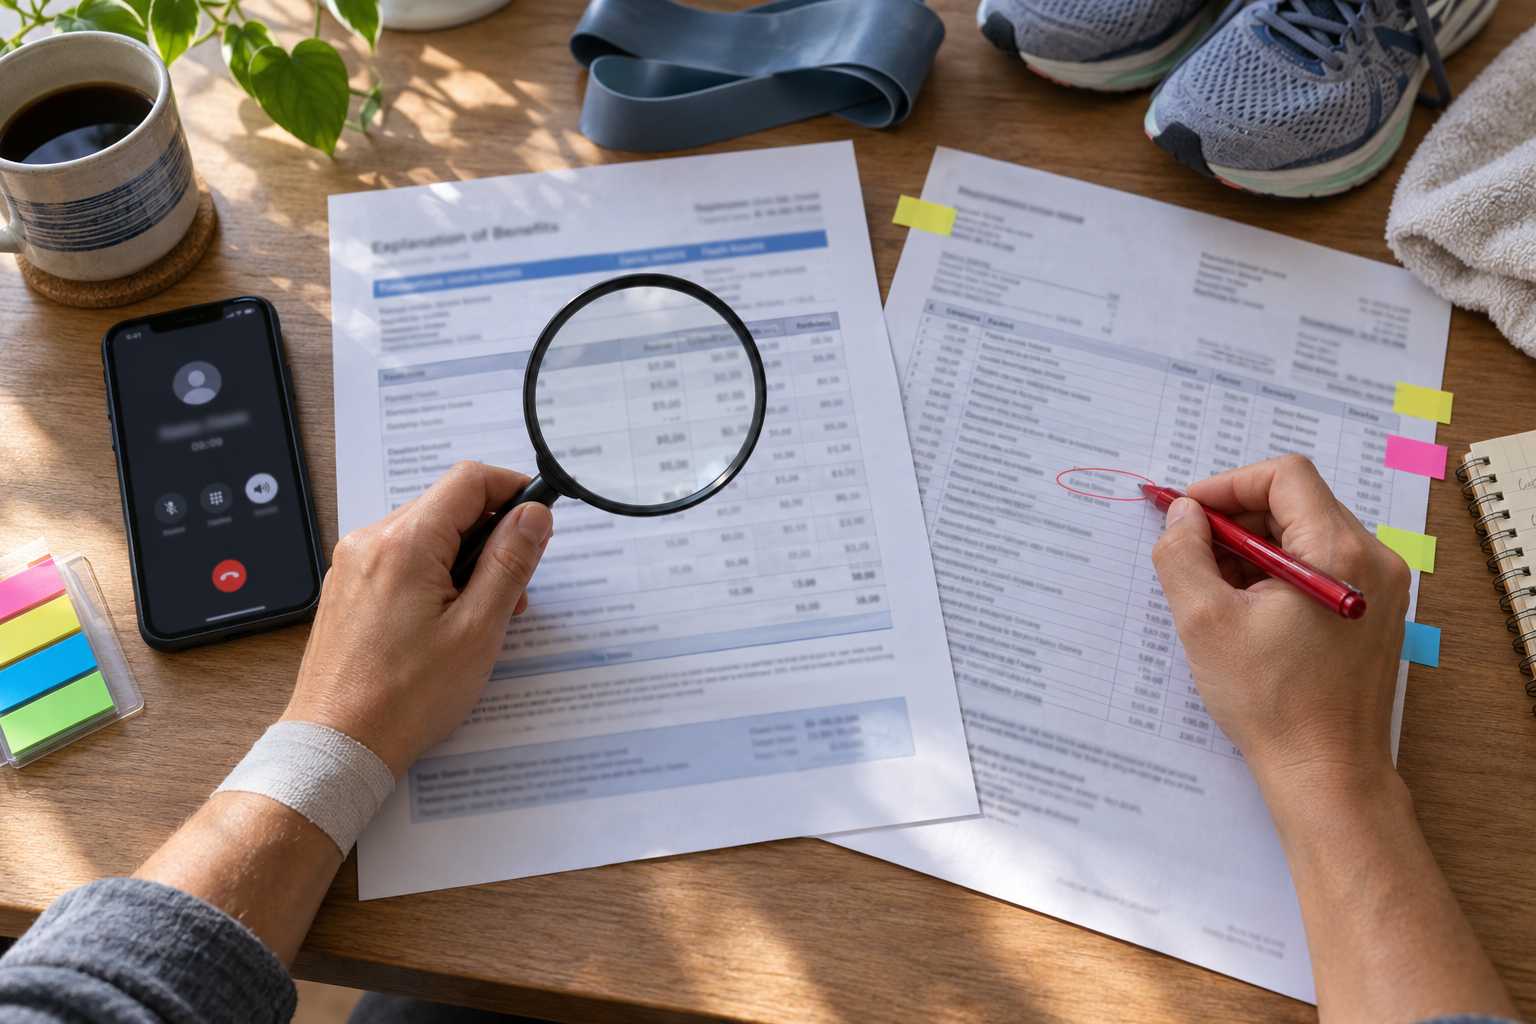
An EOB summarizes the billed charge, the insurer’s allowed amount, any discounts applied, and what the insurer paid on your behalf. It typically lists procedure or diagnosis codes, the provider name, and dates of service so you can match entries to your medical records. The patient responsibility section shows deductible, copay, and coinsurance amounts — these are the figures you might ultimately owe. Treat the EOB as a reconciliation report rather than a demand for payment.
- Billed amount: what the provider charged.
- Allowed amount: what your plan accepted as reasonable.
- Amount paid by insurer and your share.
Keep the original bill and compare it line-by-line with the EOB. If amounts or codes don’t match, that’s the point to raise questions with both the provider and the insurer immediately.
Red Flags to Watch For
Caught charges that weren’t part of your visit, duplicate entries, or services dated when you weren’t at the clinic are common mistakes. Watch for out-of-network billing slips that should have been in-network, and for denied codes that explain why an insurer paid nothing. Also check whether the EOB shows you met a deductible incorrectly or applied a copay where a preventive visit should be covered. Errors can increase your out-of-pocket cost by hundreds of dollars if left unchecked.
- Duplicate procedure codes or repeated dates.
- Incorrect patient or provider name.
- Services marked as out-of-network without prior authorization.
Flag any suspicious line items and document everything: take screenshots, save emails, and note names and dates of phone calls. Those records are crucial if you need to escalate the issue.
Steps to Fix Errors and Appeal
Start by requesting an itemized bill from the provider and compare it to the EOB. Contact the insurer’s member services to ask for an explanation of specific codes or adjustments, and ask the provider to submit a corrected claim if they billed incorrectly. If a claim denial stands and you believe it’s wrong, follow your insurer’s appeal process, submitting supporting documents and a clear statement of why the charge should be covered.
- Collect: itemized bill, medical records, and the original EOB.
- Call provider billing and insurer customer service; then follow up in writing.
- File an internal appeal, and if needed, seek external review per your plan rules.
Persistence matters: many disputes resolve after a few calls and a corrected claim. If you feel stuck, consumer advocacy groups or your plan’s ombudsman can offer guidance.
Conclusion
An EOB is a tool to understand how a claim was handled and what you might owe; read it carefully and verify each entry. Spotting and correcting errors promptly can save you money and stress after a home workout injury. Keep records, ask questions, and use the appeal process when an insurer’s decision doesn’t match the facts.