Keeping active is beneficial, but injuries happen and insurance details can be confusing. Building a straightforward checklist helps you respond quickly and limit surprises after an exercise incident. This article outlines practical coverage items, documentation tips, and cost-management steps to include in a personal checklist. Use these points to make informed calls and streamline any claims process.
Core items for your coverage checklist
Start by confirming primary policy features: deductible, copay structure, in-network provider rules, and limits for physical therapy and durable medical equipment. Note whether your plan requires prior authorization for rehab services or specialist visits and list emergency coverage rules for urgent care versus emergency department use. Identify telehealth benefits, as many providers offer quick consults that can prevent escalation. Make a short table or list in your records summarizing these key numeric limits.
Keep these essential items updated each policy year and store quick-reference copies where you exercise. A compact checklist reduces confusion when timing matters during recovery.
Gathering evidence and documenting incidents
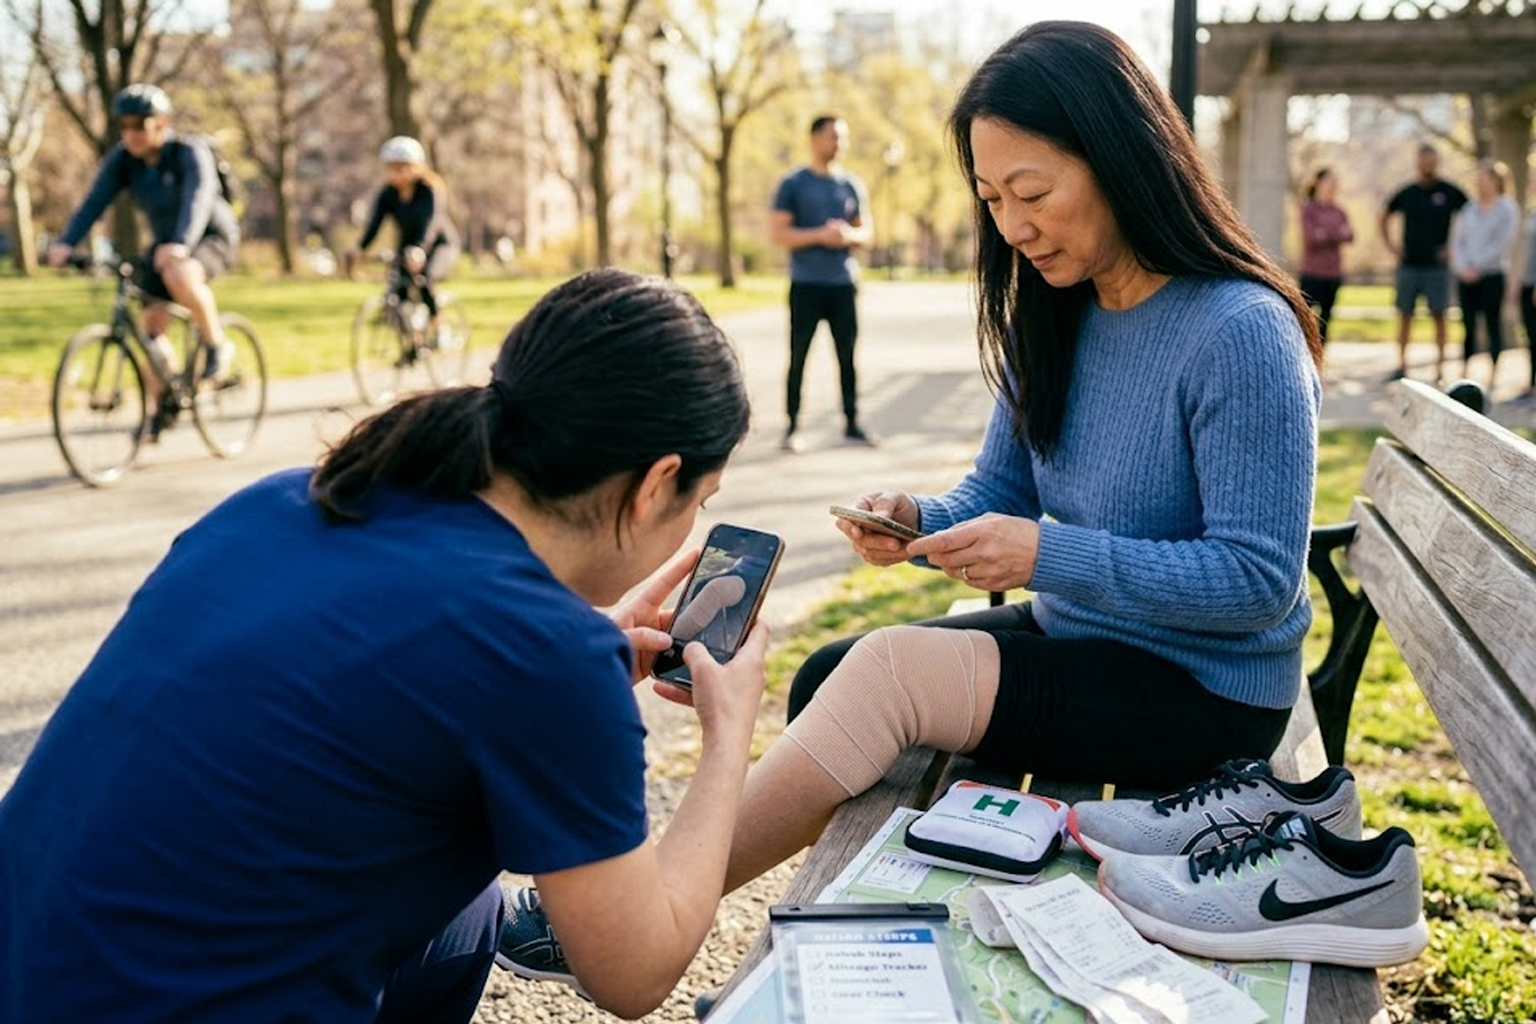
Accurate documentation supports claims and speeds approvals, so collect incident details immediately. Record the date, time, activity type, witness names, and a brief description of how the injury occurred, and photograph any visible injuries or equipment involved. Save receipts for first-response items, urgent care visits, and any follow-up appointments to track out-of-pocket spending. If you consult a clinician, request clear notes and diagnostic codes to submit with claims.
Organizing evidence in a dedicated folder or digital file helps when insurers request supporting materials. Timely, detailed records make appeals and explanations far easier.
Working with providers and managing costs
When selecting where to receive care, check provider networks and rehabilitation options to reduce surprises. Ask clinics about bundled pricing for therapy sessions or sliding-scale programs if you expect ongoing rehabilitation needs. Consider telehealth for early assessments to determine if in-person care is necessary, and verify cost-sharing differences between virtual and in-person visits. Understand referral requirements to avoid denied claims when a specialist or extended therapy is recommended.
Proactively discussing expected care paths with your insurer and providers can lower unexpected bills. Small planning steps lead to better outcomes and predictable costs.
Conclusion
Create a concise checklist you can access during or after an incident. Update it annually and keep receipts and clinician notes organized. A prepared approach reduces stress and improves claim outcomes.