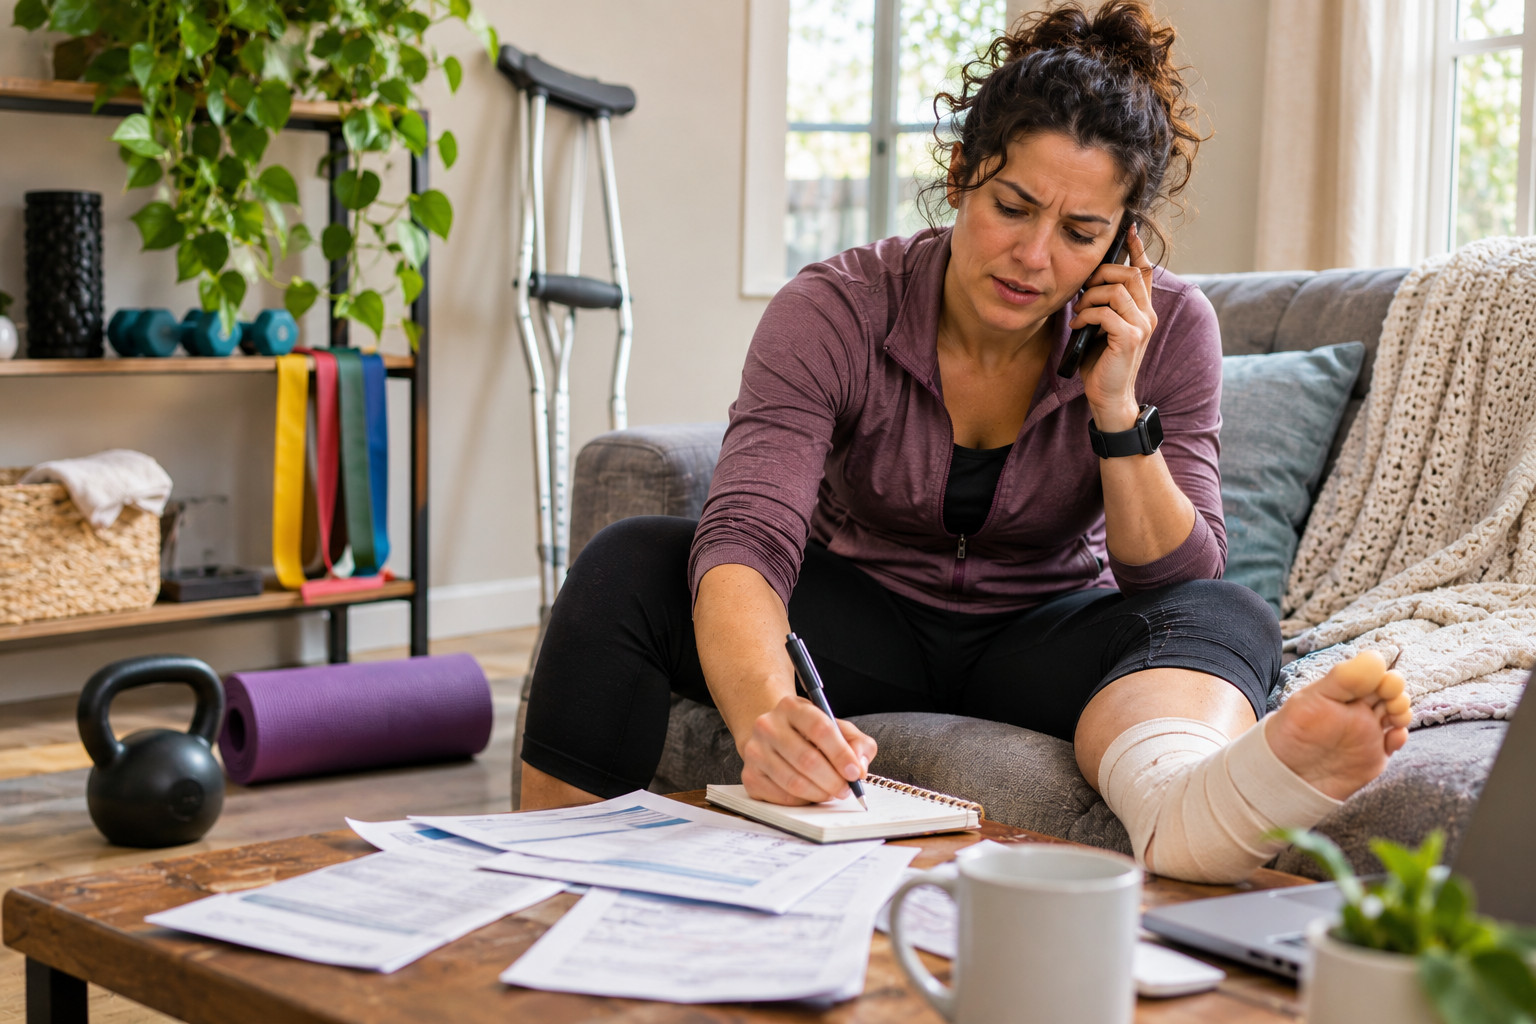
Working out at home is cheaper and more convenient, but an unexpected trip to medical care can turn that routine into a confusing bill. Knowing how your health plan handles emergency visits, follow-up care, and rehabilitation helps you avoid surprises. This article breaks down the insurance details worth checking before you set up heavy equipment or try a new routine. Read on for practical steps to protect your finances and speed your recovery.
These pointers aren’t exhaustive, but they’ll point you toward the conversations and paperwork that matter most. A little preparation today can prevent big headaches later.
Know how emergency and urgent care are covered
Not all plans treat emergency room visits and urgent care the same. Some policies use a higher deductible or steeper co-pay for ER visits, while urgent care centers may be cheaper but filtered by network rules. If you sprain an ankle or suspect a fracture after a workout, choose the level of care that fits both your injury and your plan’s cost structure.
Check your policy’s definitions of emergency conditions and whether tele-triage services are covered. Calling your insurer’s nurse line before heading to the ER can clarify whether the visit will be considered urgent or emergent.
Understand in-network providers, balance billing, and authorization rules
Balance billing is a common source of surprise costs when an out-of-network provider is involved. Even at an in-network hospital you can encounter out-of-network specialists or imaging centers with separate billing. Verify whether preauthorization is required for imaging, surgery, or specialist visits after an injury sustained at home.
Ask your insurer how they handle out-of-network charges and whether they offer dispute resolution or cost-sharing protections for emergencies. Knowing these rules helps you choose providers that minimize unexpected bills.
Rehab, physical therapy, and telehealth benefits
Recovery from a workout injury often involves physical therapy, durable medical equipment, or virtual check-ins. Policies vary in the number of covered PT visits, whether a doctor’s referral is required, and what equipment counts as durable versus non-covered. Telehealth can reduce costs for follow-ups, but not all plans treat virtual rehab equally.
Review limits on therapy visits, expected co-pays, and coverage for home-based equipment or professional home health visits. Planning your rehab within those constraints saves money and helps you recover faster.
Conclusion
Before you clear space for a home gym, read the sections of your policy that cover emergency care, provider networks, and rehab services. Call your insurer to confirm how specific scenarios are handled, and document any approvals or referrals. Being proactive reduces the risk of surprise bills and supports a smoother recovery if an injury occurs.