Figuring out whether your medical insurance will pay for in-home care can feel overwhelming, but a few organized steps make it manageable. Start by knowing the language on your policy and who provides authorization for services. Talk directly with your insurer and any prospective home-care providers before scheduling treatment. Clear communication and good documentation are the foundation of a smoother approval process.
Start with Your Policy and Primary Contact
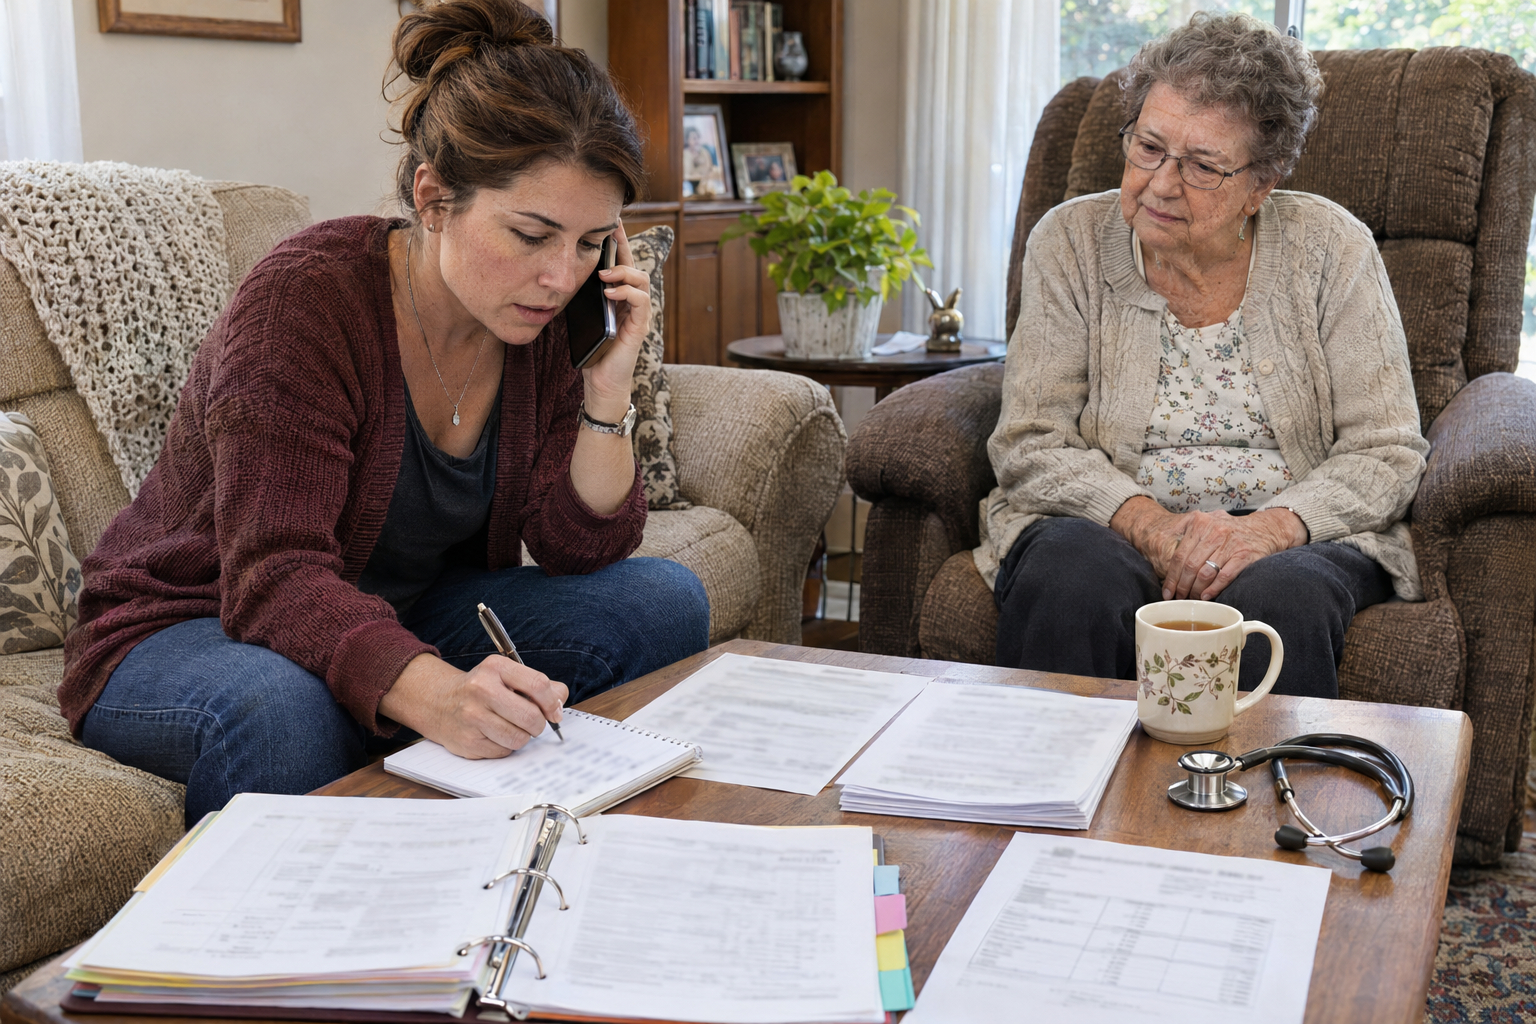
Locate your summary of benefits and the full policy document to identify sections about home health, durable medical equipment, and rehabilitation services. Look for keywords like “medical necessity,” “prior authorization,” and “network providers”—they determine what gets approved. Call the insurer’s customer service number and write down the representative’s name, date, and specific answers you receive. Those notes become useful if a question turns into a claim or an appeal later on.
Don’t assume all home-based services are treated the same; physical therapy might be handled differently than nursing visits or equipment. Confirm whether services require a doctor’s order and whether the provider must be in-network to qualify.
Gather Documentation and Clinical Justification
Insurance companies decide on claims based on clinical need and properly completed paperwork, so assemble medical records, physician orders, and a clear care plan. Request a written plan from your physician that spells out diagnosis, treatment goals, expected duration, and why home care is needed instead of clinic visits. Keep copies of any evaluations or progress notes from therapists or nurses who assess the patient at home.
- Doctor’s order specifying services and duration
- Clinical notes showing functional limitations
- Estimates or invoices for equipment or supplies
Organizing these items before you submit a claim reduces delays and helps the reviewer see the case as medically justified. A concise file makes it easier to respond quickly if the insurer asks for more information.
Filing Claims and Managing Denials
When you submit a claim, include all supporting documents and a cover letter that highlights the medical necessity and references the doctor’s order. If a prior authorization is required, get it in writing and confirm the dates and codes covered. Track claim numbers and timelines so you know when to expect a decision.
If a claim is denied, read the denial letter closely to understand the reason and whether an appeal is allowed. Prepare an appeal packet with missing documentation, a focused explanation from the treating physician, and any relevant progress notes; timely and specific appeals often succeed.
Conclusion
Being methodical makes insurance processes less confusing and more effective. Keep clear records, confirm requirements up front, and follow up promptly on questions or denials. A well-documented request greatly improves your chances of coverage.