Choosing medical insurance when you value regular exercise means balancing routine care with coverage that supports an active life. Plans differ in how they handle preventive visits, physical therapy, sports-related injuries, and fitness-related programs. Understanding those differences helps you avoid surprise bills and keeps recovery options accessible when you need them. This article walks through what to look for so your coverage complements, not complicates, your fitness goals.
Key features to check in a plan
Not all policies are built the same; some focus on low premiums while others emphasize broader networks or lower out-of-pocket costs. Look at deductibles, out-of-pocket maximums, and how visits to specialists like orthopedists or physical therapists are priced. Also confirm whether urgent care visits are covered at a lower cost than emergency room visits—useful for minor sports injuries. In-network facilities and providers matter a lot if you prefer continuity of care with a known team.
Pay particular attention to prior authorization rules and referral requirements, which can slow access to specialists. A plan with easy access to imaging and rehab services will save time and frustration when you need swift treatment. Consider whether your regular doctors and preferred clinics are in-network before you commit. These logistical details shape how quickly you can return to training after an injury.
Fitness-related benefits worth prioritizing
Some plans now include wellness perks that go beyond standard medical care: subsidized gym memberships, discounts for wearables, or reimbursement for structured programs. While these benefits shouldn’t be the sole reason to pick a plan, they can lower the true cost of staying active. Coverage for preventive screenings, nutrition counseling, and mental-health services also supports overall performance and recovery. If your routine includes high-intensity or contact sports, check how the plan handles concussion care and orthopedic referrals.
- Gym or wellness reimbursements that offset membership costs.
- Physical therapy coverage with reasonable session limits.
- Quick access to imaging and specialist consults.
These extras add practical value and encourage consistent healthy habits. When comparing policies, add the estimated value of these perks to the premium and copay math.
Practical tips for comparing plans
Start by listing your typical annual health needs: primary care visits, any chronic conditions, and the likelihood of needing injury care. Use that list to model yearly costs under each plan: premiums plus estimated copays, coinsurance, and deductible. Call providers to verify network status and ask about average wait times for specialist appointments. Don’t forget to check how appeals and pre-authorizations are handled if treatment plans change mid-year.
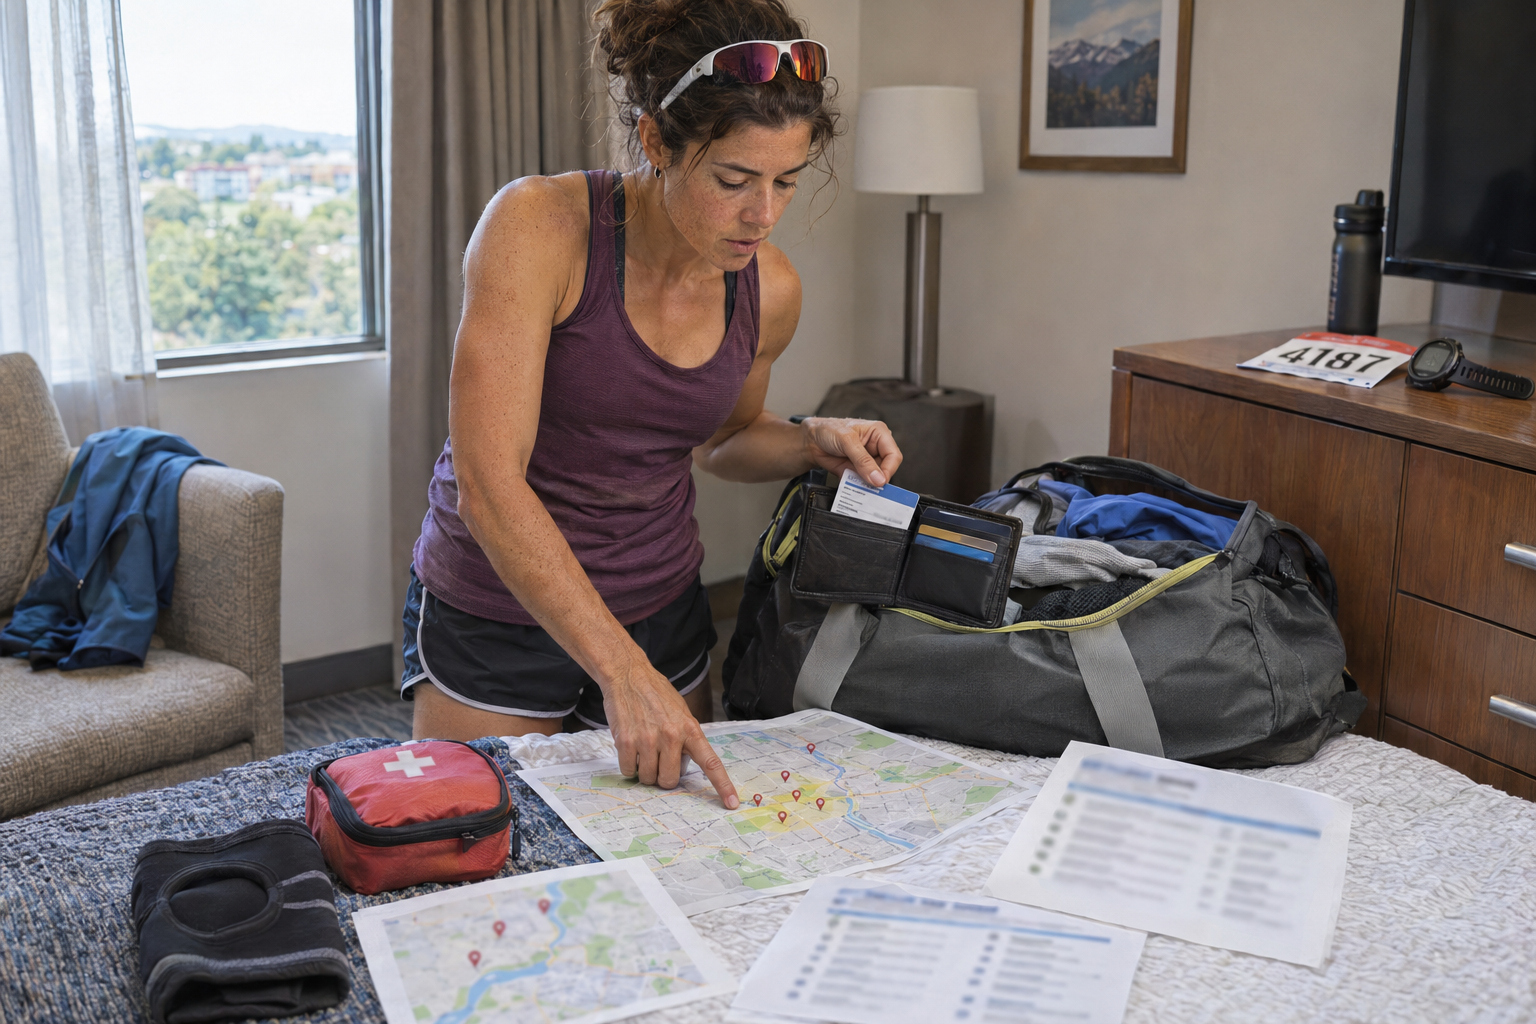
Also factor in lifestyle: if you travel frequently for races or training, a plan with broader national coverage can be worth a higher premium. Keep a folder of key policy documents and phone numbers so you can move fast when an injury occurs. Small preparations make a big difference during recovery.
Conclusion
Pick a plan that balances affordable routine care with straightforward access to specialists and rehab services. Prioritize coverage elements that match your training intensity and injury risk profile. Thoughtful comparison keeps you healthy and back in motion with fewer surprises.