Working out at home is convenient, but it changes how medical coverage may apply.
Small injuries and unexpected accidents can raise questions about who pays and when.
Before relying on a home routine for regular training or rehab, it pays to clarify benefits and limits in your plan.
This article outlines practical steps to review coverage, document incidents, and reduce financial surprises should care be needed.
Know Your Policy Basics
Start by reading the core elements of your health policy: covered services, explicit exclusions, and provider network definitions. Focus on language around accidental injuries, outpatient treatment, and rehabilitation services that commonly follow exercise-related incidents, and note any references to activity-related exclusions. Check whether durable medical equipment, assistive devices, or home modification costs are addressed when an injury affects daily function. Understanding these lines helps you set realistic expectations and avoid surprises if you need care or equipment.
Ask your insurer to confirm ambiguous wording in writing and request examples of covered scenarios if possible. Keep a copy of any clarifying correspondence with your plan for future reference and claim support.
Verify Emergency and Follow-Up Care
Emergency care coverage often differs from routine or elective services, so identify what your plan defines as urgent care and emergency treatment and how those services are billed. If you need ambulance transport, urgent imaging, or immediate physician evaluation after a fall or strain, confirm cost-sharing, prior authorization rules, and whether balance billing can occur. Telehealth and virtual triage can be a lower-cost first step for many minor injuries; check whether these services are included, count toward deductibles, and can generate referrals for in-person care. For ongoing rehabilitation, verify the number of covered physical therapy sessions, whether a treating provider must order therapy, and any caps on provider choice.
- Ambulance and ER coverage, including cost-share details
- Telehealth, urgent care options, and referral pathways
- Physical therapy limits, prior authorization, and provider network rules
Plan for out-of-network costs in cases where in-network care isn’t available quickly and identify in-network rehab providers near you. Having a list of approved facilities and clinicians speeds decision-making after an incident and may reduce surprise bills.
Documenting Incidents and Filing Claims
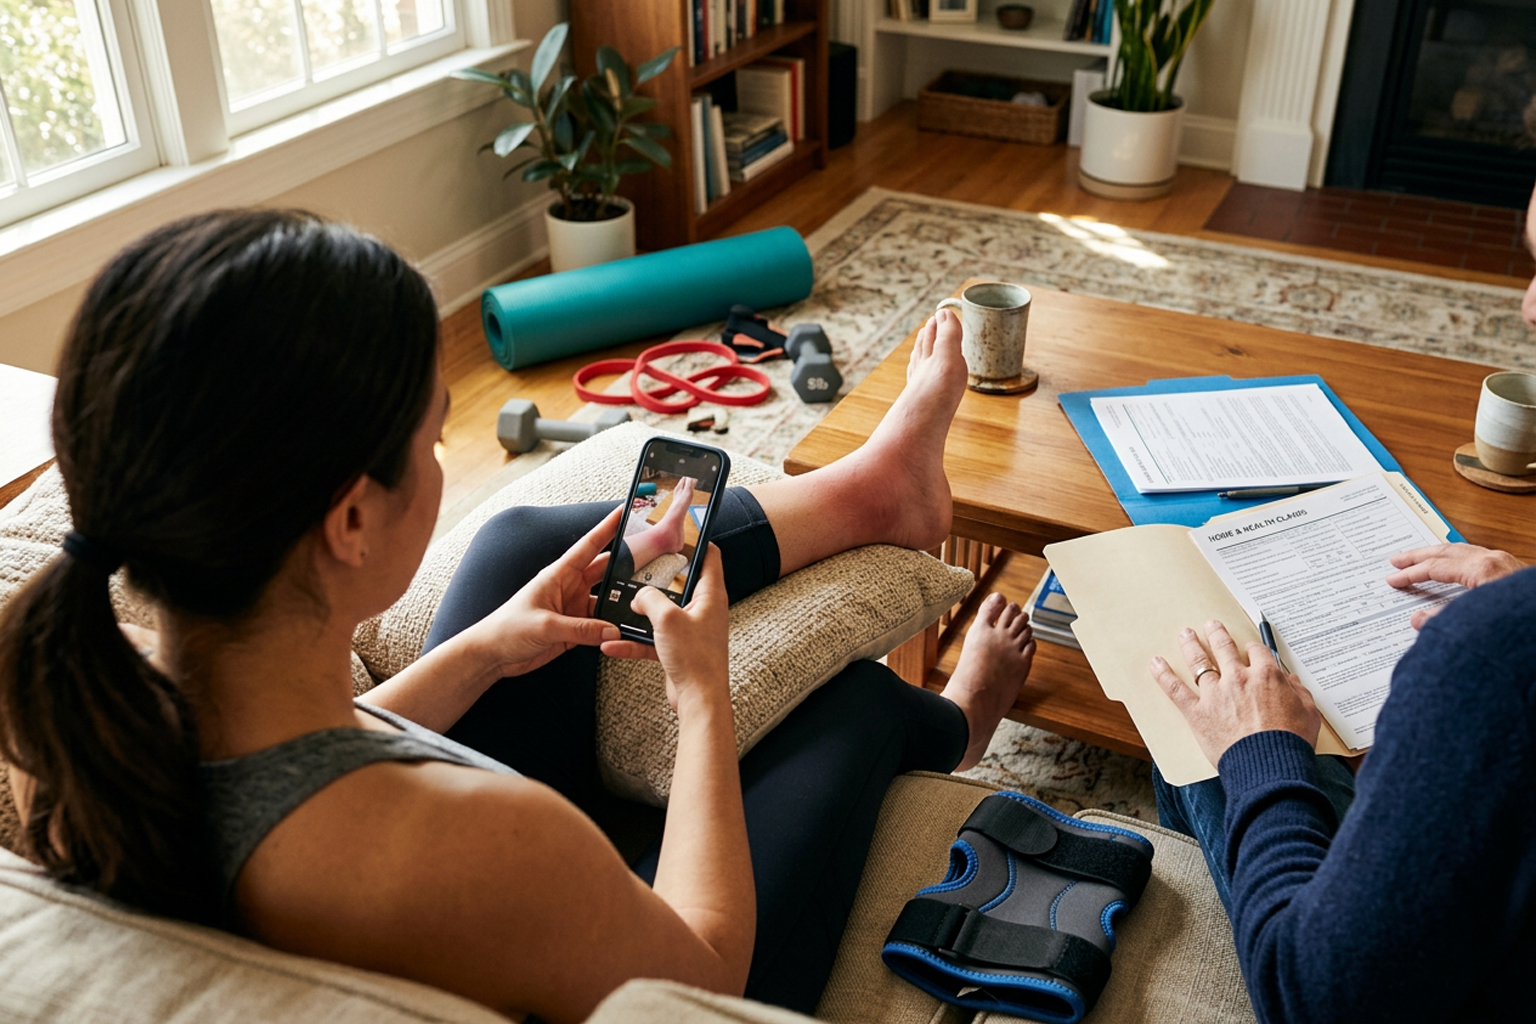
Accurate documentation matters for successful claims: record what happened, take photos of the scene and injuries, and note dates, symptoms, and progression. Seek prompt medical evaluation and request complete medical records and an itemized bill to support any claim, including diagnostic codes and provider notes that link the visit to the incident. When filing a claim, include a clear timeline, witness information if available, and any relevant medical history to avoid ambiguity about whether care relates to a preexisting condition. Keep a dedicated folder—digital and physical—for all related paperwork and correspondence, including claim numbers and phone call logs.
Follow up regularly with your insurer and the provider’s billing office until the claim is resolved, and if a claim is denied request a written explanation and appeal instructions. Consider using an employer benefits advisor or a patient advocate service if disputes become complex.
Conclusion
Review policy details and confirm ambiguous clauses in writing to reduce cost uncertainty.
Clarify emergency, outpatient, and rehab rules before embarking on intensive home training.
A little planning and documentation helps protect both your health and your finances.