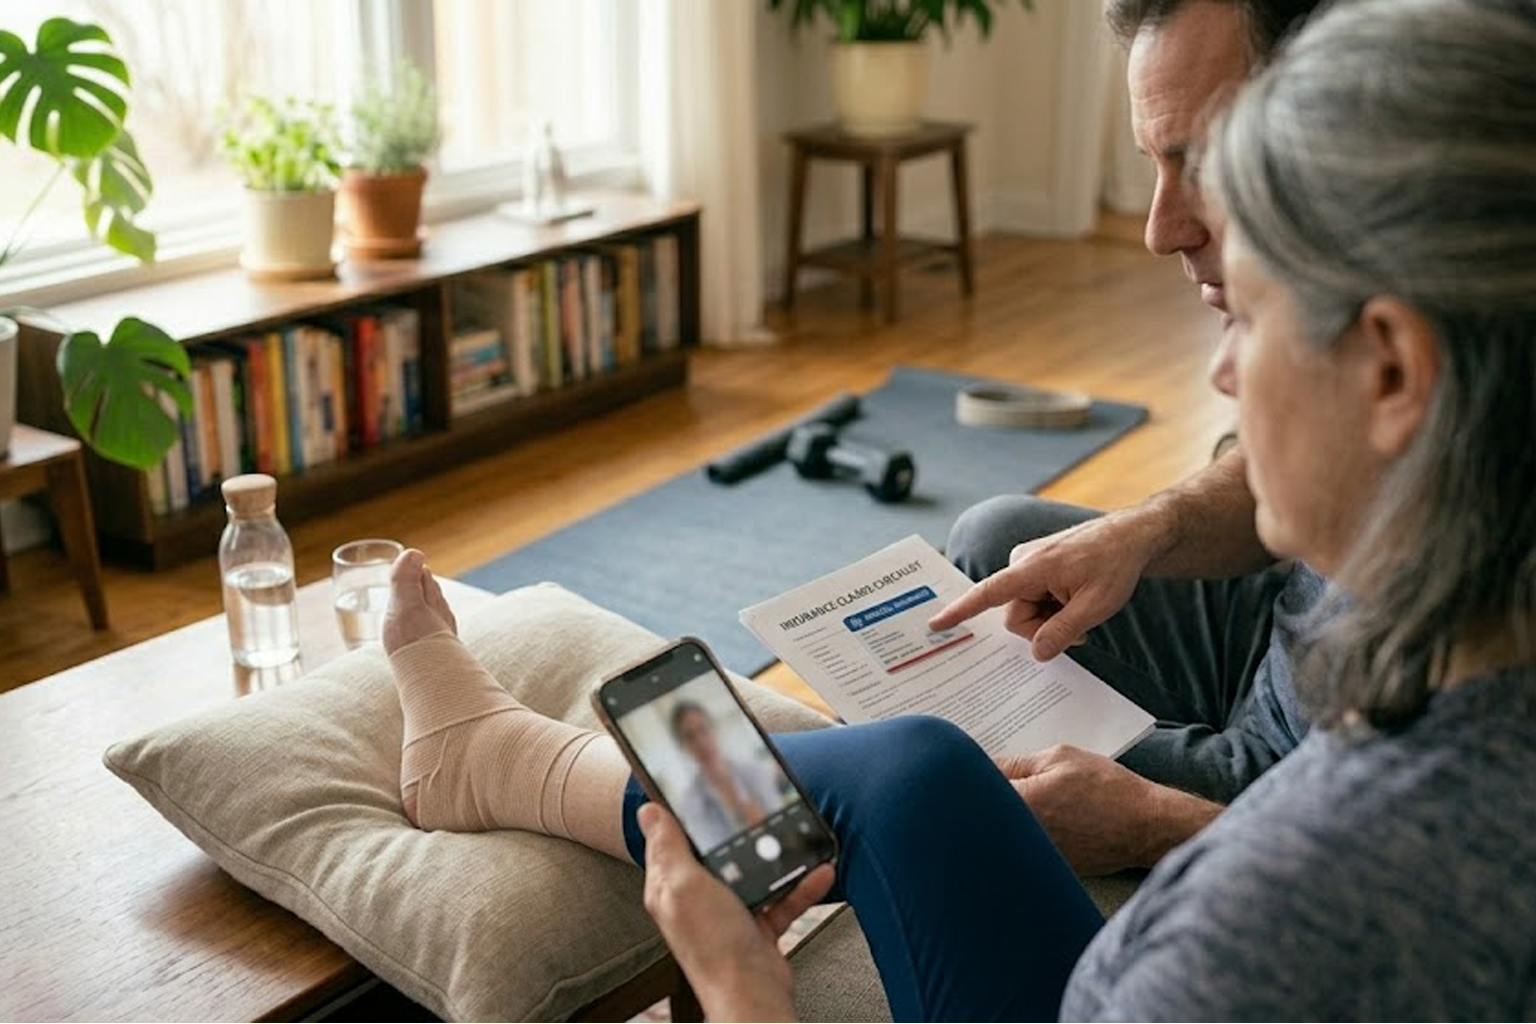
Training at home brings convenience and consistency, but it also raises questions about medical coverage when things go wrong. Understanding how your policy treats injuries, telehealth visits, and rehabilitation can limit surprises and protect your budget. This article outlines practical steps to evaluate policy features and work with your insurer after a home-exercise incident. Use these guidelines to make informed choices about care, costs, and provider access.
Why policy details matter for home workouts
Not all plans treat home-related injuries or virtual care the same way, and small differences can drive large out-of-pocket costs. Coverage definitions for emergency care, urgent care, and telehealth determine where you should seek care first. Rehabilitation benefits, durable medical equipment clauses, and prescription rules also affect recovery timelines and expenses. Spotting these distinctions before an incident helps you act quickly and confidently when care is needed.
Reviewing these elements ahead of time reduces stress and speeds decision-making. A little preparation lets you balance convenience with cost-effectiveness when choosing care.
Key policy features to check
Start by confirming your network rules, copays, deductibles, and prior-authorization requirements for physical therapy and specialist visits. Verify telehealth coverage details, including who can provide electronic visits and which services qualify. Look for exclusions tied to at-home equipment use or specific activities that could influence claim outcomes. Understanding claim submission windows and appeal procedures is also essential for resolving disputes.
- Network provider lists and out-of-network benefits
- Rehab visit limits and prior authorization rules
- Telehealth scope and permitted providers
Keeping a checklist of these features makes policy comparisons straightforward and highlights any potential gaps to address.
Working with providers and filing claims
When an incident occurs, document what happened, where you sought care, and any provider recommendations for follow-up. Choose in-network providers when possible to minimize costs, and ask care teams to submit claims promptly with clear diagnostic codes. If a service is denied, use the insurer’s appeal process and supply supporting documentation from clinicians. Staying organized and proactive often speeds approvals and reduces financial strain.
Open communication between you, your provider, and the insurer helps prevent misunderstandings and improves claim outcomes. Keep copies of all correspondence until the case is resolved.
Practical steps to limit out-of-pocket exposure
Simple actions like confirming coverage before elective treatments, using telehealth for minor concerns, and choosing urgent care over emergency rooms for non-life-threatening injuries can lower costs. Consider setting aside an emergency fund or a health savings account to cover deductibles and copays related to training mishaps. Annual policy reviews during open enrollment let you adjust plan choice based on evolving training habits and risk tolerance.
Proactive planning and smart care choices together form the best defense against unexpected bills. Small adjustments to how you access care can yield meaningful savings.
Conclusion
Know your plan’s rules for telehealth, rehab, and emergency care before you need them. Keep documentation and choose in-network providers when possible to reduce costs. Regularly review coverage as your home training routine changes.